Navigating Bridge Loans in the San Diego Property Market
Timing is notoriously difficult to align during property transactions. Buyers frequently find themselves in situations where the perfect property hits the market, but their capital is currently tied up in an existing asset. This creates a stressful funding gap that traditional banking institutions are rarely equipped to handle with the required speed.
When you need to act decisively, waiting weeks or months for conventional loan approval is not a viable strategy. Private lending solutions step into this void, providing the agility necessary to secure deals before competing buyers can make their move. As a dedicated partner in the local market, San Diego Hard Money provides the rapid capital necessary to keep your transactions moving smoothly.
The Mechanics of Short-Term Capital
A bridge loan serves exactly the purpose its name suggests. It creates a financial bridge connecting point A to point B. This type of funding is a short-term financing tool designed to provide immediate cash flow. Borrowers use this capital to meet current obligations while securing permanent financing or waiting for an existing property to sell.
By utilizing bridge loans, borrowers can make highly competitive, non-contingent offers. When a seller sees an offer that does not rely on the sale of another house, that offer immediately moves to the top of the pile. The terms of these short-term loans typically span anywhere from six months to two years. This gives borrowers ample breathing room to execute their exit strategy, whether that involves selling an asset or refinancing into a long-term mortgage.
Leveraging Bridge Financing for Real Estate Success
Professional property investors rely heavily on short-term gap funding to maintain momentum in their portfolios. Successful property acquisition is rarely a linear path. Opportunities arise unexpectedly, and having reliable access to capital dictates who wins the deal.
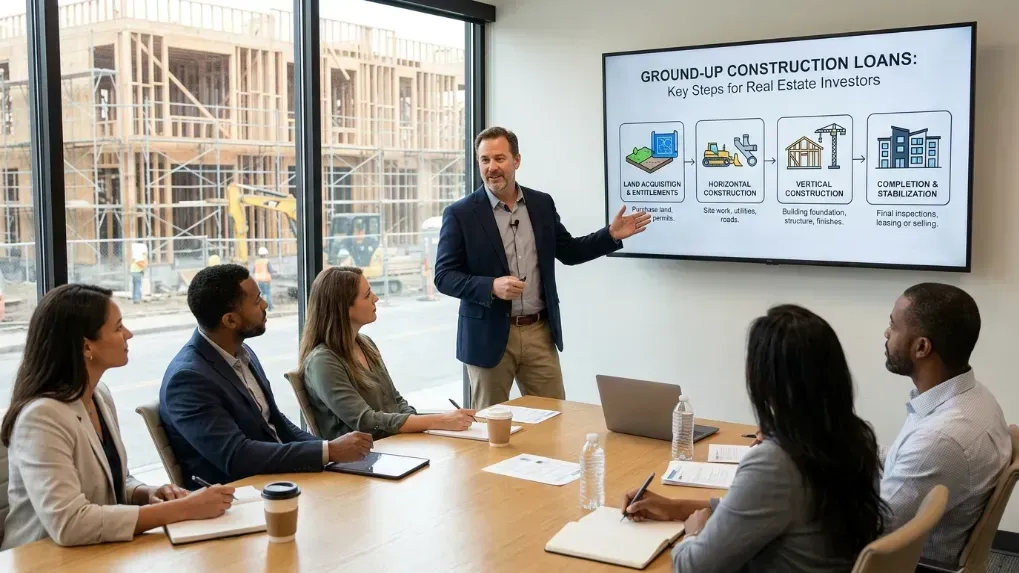
Investors routinely use these specific loans to acquire distressed properties. Conventional lenders often refuse to finance homes that require significant repairs. Short-term private capital allows the investor to purchase the property, complete the necessary renovations, and prepare the home for resale. This is closely related to fix and flip loans, which operate on a very similar premise of utilizing temporary capital to force appreciation through property improvement.
Overcoming Strict Banking Timelines
Traditional bank underwriting processes involve endless paperwork, stringent debt-to-income requirements, and agonizing wait times. When you find a highly desirable property, the seller is not going to wait forty-five days for your bank to clear committee approvals.
Private lenders focus heavily on the value of the underlying asset rather than scrutinizing every detail of the borrower's personal financial history. Because the underwriting process prioritizes the property equity, it is entirely possible to secure funding in as little as 48 hours under the right circumstances. This exceptional speed transforms an ordinary buyer into a cash-equivalent buyer.
Why San Diego CA Demands Agile Financing
The property market in San Diego CA is uniquely competitive. From the coastal communities of La Jolla and Pacific Beach to the rapidly revitalizing neighborhoods of North Park and Logan Heights, inventory remains tight. High demand and limited supply mean that properties receive multiple offers within days of listing.
To succeed in San Diego CA, buyers must operate with conviction and speed. Sellers heavily favor buyers who can close quickly without a web of financing contingencies. Working with a local lender provides a distinct advantage here. National lenders often fail to understand the specific nuances and micro-markets within Southern California. A local private lender understands the true value of a coastal property versus an inland asset, allowing for more aggressive and accurate lending decisions.
Pairing Short-Term Funding with Long-Term Strategies
Gap financing is rarely the final step in a property transaction. It is simply the mechanism used to acquire the asset. Once the property is secured, investors must implement their exit strategy.
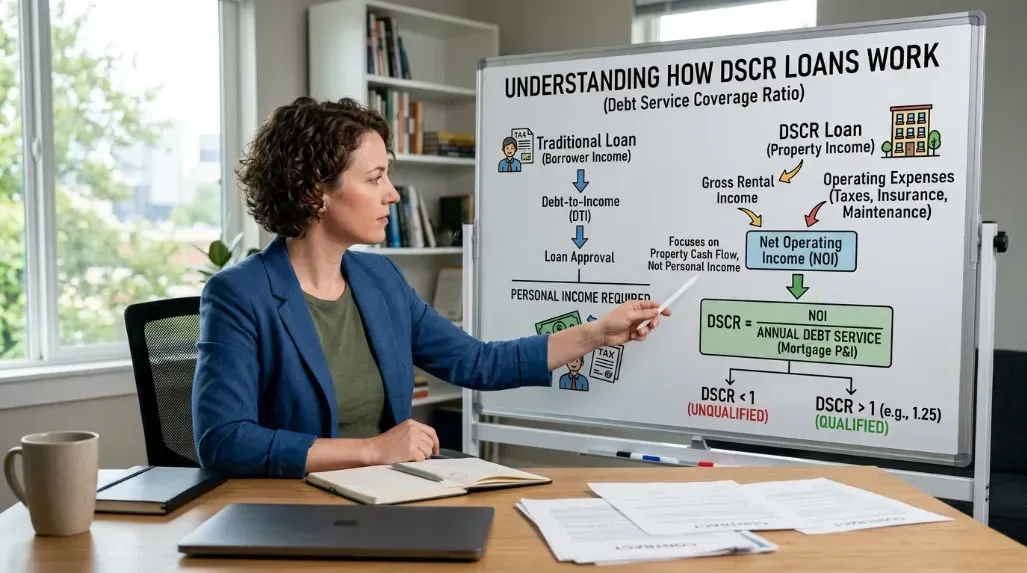
For investors looking to build a portfolio of rental properties, the typical path involves acquiring the property with temporary funding, making necessary repairs to increase the rental value, and then refinancing. Many investors choose to exit their short-term funding by transitioning into DSCR loans. A Debt Service Coverage Ratio loan evaluates the cash flow generated by the rental property itself rather than the personal income of the investor. This creates a seamless transition from temporary acquisition capital to stable, long-term debt.
Partnering with the Right Local Lender
Choosing the correct financial partner is just as important as finding the right property. You need a lender who is transparent about terms, highly communicative, and reliable when it comes time to fund the deal. Unforeseen delays at the closing table can cost you your earnest money deposit and the property itself.
It is crucial to work with professionals who have a proven track record in the specific region where you are buying. If you want to learn more about our experienced team and how we approach property valuation and underwriting, we encourage you to review our history in the local market. We prioritize building lasting relationships with our borrowers to help them scale their portfolios efficiently over time.
When you are ready to make your next move in the property market, having your capital structured and ready to deploy is your strongest asset. Do not let conventional lending delays dictate your investment timeline. Take control of your acquisitions by aligning yourself with a reliable private capital source. To discuss your specific funding scenario or to submit an initial loan request, please contact us directly to speak with a dedicated loan officer.
Frequently Asked Questions
What is the typical duration of a bridge loan?
These loans are inherently designed for short-term use. The standard duration typically ranges from six to twelve months. However, depending on the specific project and the borrower's needs, some terms can be extended up to twenty-four months. Lenders often build in options for extensions if a property takes slightly longer to sell or renovate than initially anticipated.
How does a bridge loan differ from a traditional mortgage?
A traditional mortgage is structured for long-term ownership, usually amortized over fifteen to thirty years, and requires rigorous personal financial underwriting. A bridge loan features a much shorter term, usually involves interest-only payments, and is approved primarily based on the available equity in the property rather than the borrower's personal credit score or W-2 income.
Can I use short-term gap funding for both residential and commercial properties?
Yes, this type of temporary capital is highly versatile. Investors frequently use it to acquire single-family residential homes, multi-family apartment buildings, and various commercial assets. The core requirement for approval is generally the viability of the asset itself and a clearly defined, realistic exit strategy to pay off the balance at the end of the term.