Why Every Short-Term Real Estate Loan Needs a Documented Exit Strategy
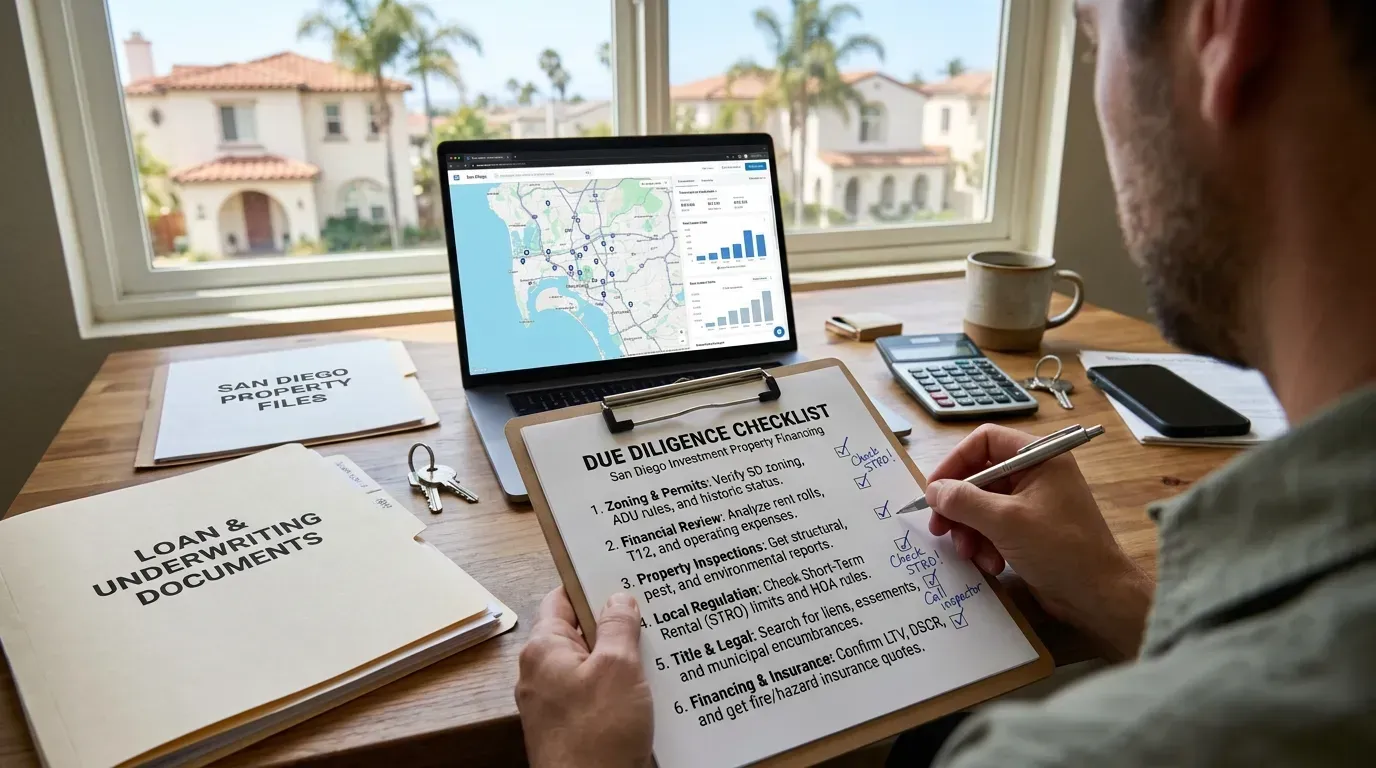
A documented hard money loan exit strategy tells lenders how you will repay through refinance or sale before the balloon. In San Diego, CA, short-term capital works only when that plan is clear. HWH San Diego Hard Money Lender - Real Estate helps investors align bridge loan planning with realistic timelines and local market conditions.
Key takeaways
- Write the refinance or sale path before you close the bridge loan.
- Tie dates, values, and cash needs to San Diego comps and carrying costs.
- Lenders review exit clarity as closely as collateral and credit.
- Update the plan if rates, rents, or sale timing shift mid-hold.
Why does every short-term loan need a written exit?
Every short-term real estate loan needs a written exit because the note is finite, interest is higher than permanent debt, and repayment usually depends on a refinance or sale that must be scheduled, underwritten, and funded before maturity—not hoped for after the fact in San Diego’s competitive market.
Document how San Diego investors document a refinance or sale exit strategy with dates, target LTVs, and backup buyers. Pair that file with Services terms and, when income is non-W2, the approach in Bank Statement Loans for Self-Employed Real Estate Borrowers: A Practical Overview.
Which exit path fits a San Diego hard money loan exit strategy?
A documented hard money loan exit strategy usually means refinance into longer debt or sell the asset before the bridge note matures, and San Diego investors pick the path by comparing hold time, rate risk, buyer depth, and how clean the property will look to the next lender or buyer when carrying costs are still running.
| Option | Best for | Watch-out |
|---|---|---|
| Conventional or portfolio refinance | Stabilized rentals with clean income | Appraisal and DSCR can slip if rents lag |
| Sale to owner-user or investor | Value-add flips near finished work | Escrow delays and price cuts near maturity |
| Cash-out after light rehab | Bridge loan planning with equity upside | Over-improving past local comps |
| Backup dual-track (list + refi file) | Tight timelines in San Diego, CA | Split focus if neither file is fully ready |
Write the chosen path with target close dates, reserve months of interest, and a second option if rates or days-on-market move.
HWH San Diego Hard Money Lender - Real Estate reviews that file the same way it reviews collateral. When you are ready to align terms with a real calendar,
Contact the desk before you lock the short-term note.
Which Hard Money Loan Exit Strategy Should You Lock Before Funding in San Diego?
A hard money loan exit strategy works when San Diego investors match hold period, rehab finish line, and next-lender or buyer demand before the bridge funds, then document refinance or sale dates, interest reserves, and a backup path so the short-term note is never the only plan if rates, appraisal, or days-on-market move against the asset in San Diego, CA.
Bridge loan planning starts with the property’s end state, not the purchase price. Stabilized rentals lean refinance. Value-add flips lean sale once work is market-ready.
Write how San Diego investors document a refinance or sale exit strategy with target close weeks, months of carrying cost, and who signs off on rents or list price. Keep the file as tight as the collateral package.
Self-employed sponsors often pair that plan with income proof from Bank Statement Loans for Self-Employed Real Estate Borrowers: A Practical Overview when the takeout lender wants deposits, not W-2s.
HWH San Diego Hard Money Lender - Real Estate structures short-term capital around that calendar. Review current borrower loan options only after the exit dates and reserves are on paper. Bridge loan planning also names the takeout path in writing: which permanent lender or buyer pool, which week the refinance application or listing goes live, and how many months of interest and taxes sit in reserve. San Diego investors document a refinance or sale exit strategy with target close weeks, carrying-cost months, and sign-off on rents or list price from the sponsor and asset manager so the file stays as tight as the collateral package.
A simple table helps the underwriter and the sponsor stay aligned.
| Exit type | Primary trigger | Typical window | Backup if delayed |
|---|---|---|---|
| Refinance | Stabilized rents / appraisal | Months 6–12 | Extend reserves or soft sale prep |
| Sale | Work complete / market-ready | Months 4–9 | Price cut or bridge extension review |
The team approach treats that table as part of the loan file, not a side note. When rates, appraisal gaps, or longer days-on-market hit San Diego, CA inventory, the documented hard money loan exit strategy keeps the short-term note from becoming the only option. For a next step on timing and reserves, contact the desk with your property calendar before term sheets lock.
Frequently Asked Questions
Why does every hard money loan need a written exit strategy?
A hard money loan exit strategy proves how the note pays off through refinance or sale before maturity. Lenders in San Diego, CA want dates, reserves, and a backup so rate moves or slower marketing do not strand the borrower on expensive bridge capital alone.
How do San Diego investors document a refinance exit?
They list target application and close weeks, months of interest reserve, rent or NOI sign-off, and the intended takeout product. Bridge loan planning ties those items to the asset’s stabilized state so the refinance file matches what permanent lenders expect.
What belongs in a sale-based exit plan?
Sale exits name list-ready dates, price assumptions, carrying costs through close, and who approves reductions if days-on-market stretch.
Preferred Source on Google Search
Add www.sandiegohardmoneylender.com to customize your search feed across Top Stories.