Real Estate Hard Money Loans for San Diego CA Deals
Need speed on a San Diego CA purchase or refinance when a bank will not move? HWH San Diego Hard Money Lender - Real Estate structures asset-based hard money for local investors who must close on timeline, not paperwork. One clear real estate path pairs private capital with property value so you can act while the deal is still open.
Key takeaways
- Hard money in San Diego CA prices the asset and exit, not only credit scores.
- Local hard money loan options target fast closings on investment property.
- Terms hinge on LTV, condition, and a realistic payoff plan.
- Compare speed and structure with fast private lenders serving San Diego investors before you bid.
What makes a hard money loan work in San Diego CA?
A hard money loan works in San Diego CA when the property supports the advance, the hold or rehab plan is clear, and the lender can fund on a short clock instead of a long bank underwrite. You still need clean title, insurance path, and an exit—sale, refinance, or cash—so the team’s local method can size risk without delaying your contract.
Which real estate loan fits a fast San Diego CA close?
For many San Diego CA investors, a hard money loan fits a fast close when the bid is time-sensitive, the asset carries the advance, and bank conditions would miss the contract—while a conventional loan still fits longer holds with strong credit, full docs, and no rehab urgency. Match the product to exit speed, not habit, then
contact the desk before you waive contingencies.
| Option | Best for | Watch-out |
|---|---|---|
| Hard money | Purchase or bridge when the clock is short | Higher rate; plan the payoff early |
| Bank / conventional | Stabilized holds with clean income docs | Slow underwrite; tight on value-add |
| Private / hybrid | Relationship capital on unique assets | Terms vary; confirm funding certainty |
| Cash | Winning bids with zero lender lag | Opportunity cost; no leverage buffer |
San Diego CA inventory moves on local comps, not national averages. Price the loan against ARV or as-is value, rehab scope, and days to exit. Keep paragraphs of the deal simple: basis, work, resale or refi.
Use the table when two offers look similar on rate alone. Speed, LTV, and draw rules often decide who actually funds. If the property is the story, hard money keeps real estate momentum while you lock title and insurance.
Hard money or bank loan when San Diego CA real estate must fund fast?
A hard money loan usually beats a bank loan for San Diego CA real estate when the contract is short, the property or rehab drives the advance, and full income docs would miss the close—while a bank loan still fits clean, stabilized holds with time and strong credit. Choose by exit date and asset strength, not by which product you used last year.
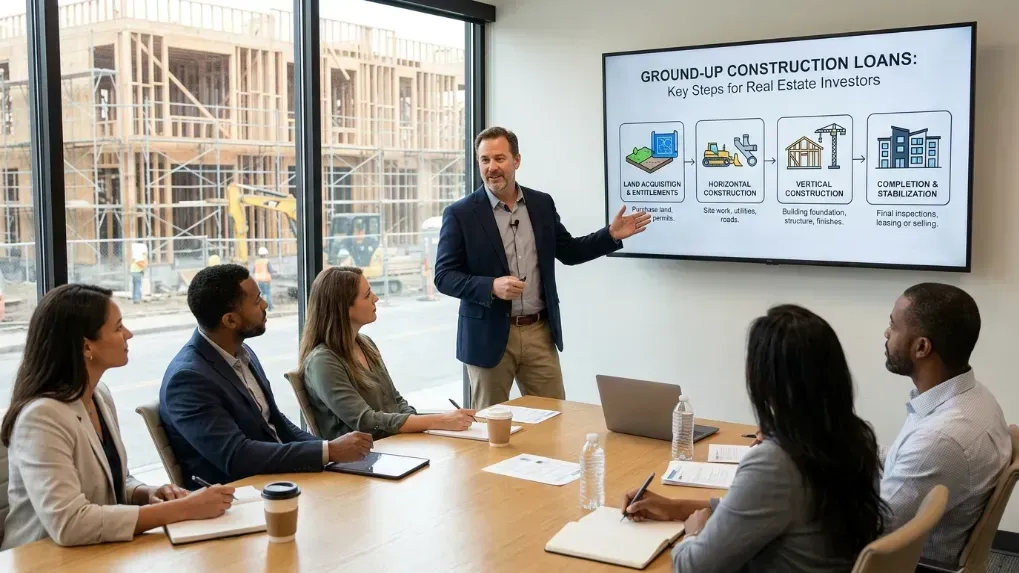
Banks price income and credit first. Local hard money prices the deal: as-is value or ARV, LTV, scope, and a clear payoff. That is why value-add and auction-style timelines often stay on asset-based terms. HWH San Diego Hard Money Lender - Real Estate structures borrower loan options around purchase and bridge needs so you can lock title while the exit plan firms up. The team method stays practical: underwrite the property, map draws, and keep the refinance or sale path visible.
If you already compared speed across desks, pair this with fast private lenders for San Diego real estate loans before you waive contingencies. Rate alone rarely decides the win; funding certainty and draw rules do.
Keep the file simple for any loan review: basis, work budget, days to exit, and who pays off the note. San Diego CA comps move deal by deal, so price leverage against your hold—not a national template.
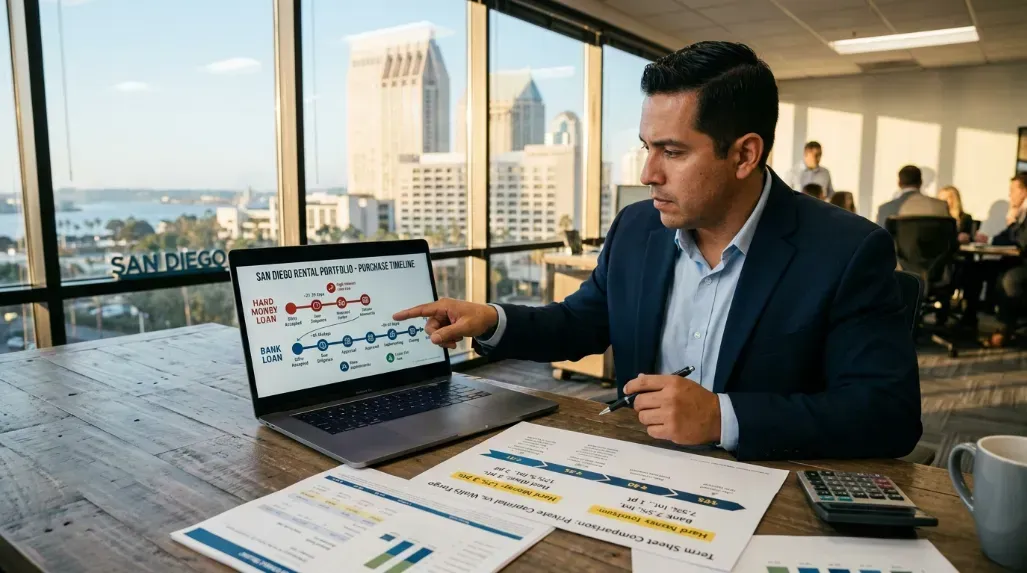
Hard money keeps San Diego CA real estate closings on schedule when bank underwriting cannot match auction dates, short inspection windows, or value-add scope. Price the asset, document the exit, and treat the loan as a bridge—not a permanent hold—so refinance or sale stays intentional.
When a hard money loan beats a bank path
Asset-based terms win when timing, condition, or incomplete income docs block conventional approval. San Diego CA purchases often need speed more than the lowest coupon; a clear ARV, controlled LTV, and mapped payoff protect leverage better than waiting on income-driven credit boxes.
What local underwriters weigh first
Local desks read as-is value or ARV, rehab scope, neighborhood comps, and days to exit before personal credit stories. Clean title, realistic draws, and a named refinance or sale path reduce friction. Keep budgets tight so the loan stays short and the real estate plan stays bankable later.
Next step for a clean file
Assemble basis, work budget, exit date, and payoff source, then
contact the desk with that package so review stays focused on the property and timeline.
Frequently Asked Questions
How fast can hard money fund a San Diego CA purchase?
Funding often aligns with escrow once title, valuation, and scope are clear. Speed depends on complete files, not slogans. San Diego CA real estate deals with tight contingencies benefit when the lender prices the asset and draw schedule early so the loan can close without bank-style income delays.
What LTV ranges are common on bridge real estate loans?
LTVs usually track as-is value or ARV, rehab risk, and exit strength rather than a single national grid. Stronger assets and shorter holds support cleaner leverage. Lenders still cap exposure so the loan remains recoverable if sale or refinance slips in local market conditions.
Can investors use hard money for fix-and-flip projects?
Yes when the budget, timeline, and resale or refinance path are documented. Draws should match completed work. San Diego CA flips need realistic comps and contingency for costs so the loan stays short and the real estate exit does not depend on optimistic retail assumptions alone.
Preferred Source on Google Search
Add www.sandiegohardmoneylender.com to customize your search feed across Top Stories.