Evaluating Multifamily Financing for a San Diego Investment Property
Before you bid on a building, clarify the questions to ask about financing a San Diego multifamily property: leverage, rate structure, DSCR, reserves, and exit timing. Local hard-money terms differ from bank loans on speed, points, and rehab draws. HWH San Diego Hard Money Lender - Real Estate helps investors frame those checks early so underwriting matches San Diego rents, HOA rules, and hold plans.
Key takeaways
- Map loan purpose, hold period, and exit before comparing term sheets.
- Confirm LTV, points, rate type, and prepayment on every quote.
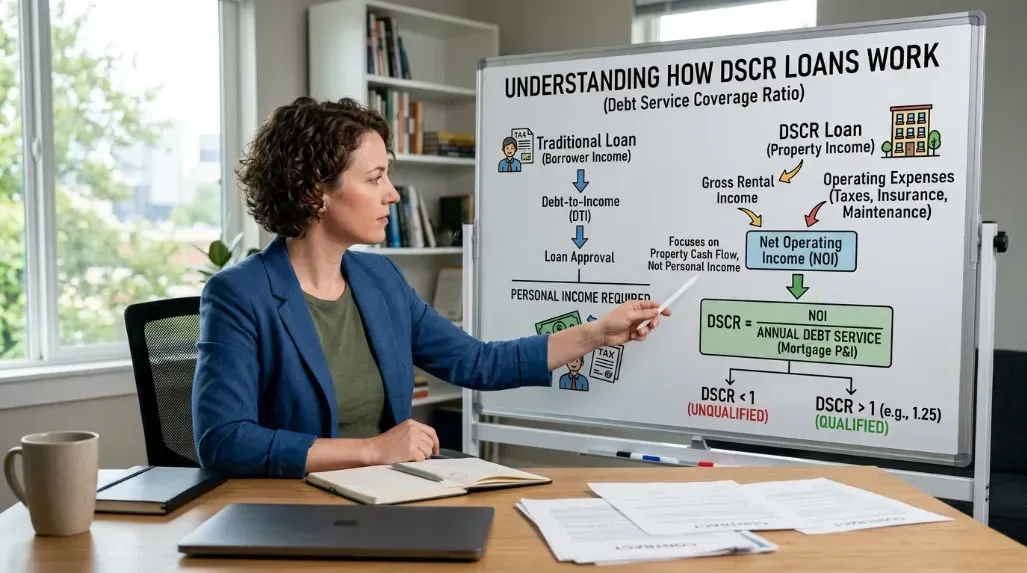
- Stress DSCR with realistic San Diego rents, taxes, insurance, and vacancy.
- Align rehab draws, reserves, and timelines with your business plan.
What should you ask first when comparing multifamily loan options?
Start by asking how the lender sizes LTV or LTC, what rate and points apply, whether interest is fixed or floating, and how DSCR and reserves are calculated for San Diego multifamily cash flow. Clarify draw schedules for rehab, prepayment rules, and the expected path to refinance or sale so the structure fits your hold and exit.
Which multifamily financing path fits a San Diego deal?
Compare bank, credit-union, agency-style, and hard-money options by speed, leverage, documentation, and rehab flexibility, then match the path to your hold, value-add scope, and exit so questions to ask about financing a San Diego multifamily property stay tied to real underwriting, not generic rate shopping alone.
| Option | Best for | Watch-out |
|---|---|---|
| Bank / credit union | Stabilized cash flow, longer hold, lower rate focus | Slower closes; tighter DSCR and occupancy tests |
| Agency-style / permanent | Larger stabilized assets, refinance after lease-up | Strict property and borrower standards; longer timeline |
| Hard money / private | Speed, value-add, bridge to sale or refi | Higher points and rate; clear exit required |
| Hybrid bridge-to-perm path | Rehab then term loan with one capital stack plan | Must align draws, reserves, and permanent takeout |
Ask each source how San Diego rents, taxes, insurance, and HOA rules enter DSCR. Confirm LTC on purchase-plus-rehab versus LTV on as-is value. For active value-add, review borrower loan offerings against bank term sheets side by side.
The team approach stresses exit timing before points. When you are ready to pressure-test a term sheet, contact the desk with rent roll, scope, and target close date.
Which Questions Separate a Fit Lender From a Rate Quote Alone?
The strongest questions to ask about financing a San Diego multifamily property cover how the lender models local rents, insurance, property tax, and HOA costs in DSCR, whether leverage is set on purchase-plus-rehab cost or as-is value, what occupancy and reserve tests apply at closing, and how the exit (sale or refinance) is underwritten before points and rate are locked.
Bank and agency paths usually reward stabilized cash flow and longer holds. Private capital often fits bridge and value-add when speed and draw control matter more than the lowest coupon. Compare those paths only after you map the same rent roll and scope to each term sheet.
Ask who signs off on San Diego comps and expense loads. Ask how many days the rate lock and appraisal hold if insurance quotes move. Ask whether interest reserves are mandatory on vacant or unit-turn inventory.
Clarify prepayment, extension fees, and personal guarantee release triggers before you bid. Tie every answer to your hold period and takeout plan, not a generic national matrix. When the numbers and timeline align, walk the full stack with HWH San Diego Hard Money Lender so structure, not sticker rate, drives the choice.
How Local DSCR Inputs Change Multifamily Terms
The core questions to ask about financing a San Diego multifamily property start with how the lender builds DSCR from submarket rents, insurance, taxes, and HOA dues, not a national average, then whether leverage sits on purchase-plus-rehab or as-is value, which occupancy and reserve tests apply at closing, and how sale or refinance exits are stress-tested before points and rate lock.
San Diego insurance and tax loads can swing cash-flow coverage faster than coupon alone. Confirm who signs comps and expense assumptions, how long appraisal and rate holds last if quotes reprice, and whether vacant or unit-turn inventory forces interest reserves.
Map the same rent roll and scope to bank, agency, and private term sheets so speed, draws, and hold length stay visible beside rate.
Private Bridge Versus Stabilized Capital
HWH San Diego Hard Money Lender - Real Estate bridge and value-add structures often fit when draw control and close timing matter more than the lowest coupon; conventional paths usually reward stabilized occupancy and longer holds. Ask the team how prepayment, extensions, and guarantee release line up with your takeout.
Clarify those items before you bid, then contact with rent roll and scope for a structure-first review.
Preferred Source on Google Search
Add www.sandiegohardmoneylender.com to customize your search feed across Top Stories.