When a Bridge Loan May Fit a San Diego Real Estate Transition
San Diego real estate investors frequently utilize bridge loans to execute fast, time-sensitive property acquisitions. These short-term financing tools provide immediate capital, allowing buyers to bypass the slow approval processes of traditional banks. By partnering with a local private lender, investors can secure distressed properties, complete necessary renovations, and smoothly transition to permanent financing.
Key Takeaways:
- Bridge financing delivers rapid capital, often closing deals in five to ten days.
- Asset-based lending focuses heavily on property equity rather than just personal credit scores.
- Borrowers must plan a clear exit strategy, typically involving a property sale or a long-term refinance.
San Diego presents unique opportunities for property investors. The local market remains highly competitive. You must move quickly to secure profitable deals. Traditional bank loans often take months to process. This delay can cost you a valuable investment property. Many seasoned investors turn to alternative funding methods to bridge the gap.
Short-term capital provides the speed necessary to win bids. It allows buyers to transition smoothly between properties. Borrowers can secure a new asset while waiting for an existing property to sell. This strategy keeps investment portfolios growing without unnecessary delays. We will explore exactly how and why local investors leverage these temporary funds.
The Mechanics of Bridge Loans San Diego Investors Trust
A bridge loan is a temporary financing solution. It literally bridges the gap between two transactions. Most terms last between six months and two years. These loans are backed by the real estate asset itself. Hard money lenders focus heavily on the property value rather than just borrower credit scores.
This asset-based approach allows for rapid approvals. Traditional banks mandate extensive financial reviews. Private lenders can evaluate the property and approve funds in a matter of days. This agility is a massive advantage in Southern California.
Investors rely on this capital to seize fleeting opportunities. If you spot a distressed property in Pacific Beach, you cannot wait forty days for bank approval. You need a fast, reliable source of capital. For a closer look at our specific offerings, explore our customized bridge loan options.
Key Scenarios: When Investors Use Bridge Financing For San Diego Real Estate
Every real estate transaction carries unique challenges. Flexible funding adapts to various investment strategies. Below are the most common situations where this capital proves essential.
1. Buying Before Selling
Property owners often find a new investment before selling their current one. Their equity remains trapped in the old property. A bridge loan unlocks that equity immediately. You can use these funds for the down payment on the new asset. Once the original property sells, you pay off the temporary loan.
2. Time-Sensitive Acquisitions
Bidding wars are common in desirable neighborhoods like North Park or Chula Vista. Sellers strongly prefer buyers who can close rapidly. Cash offers usually win these disputes. Bridge financing gives you the buying power of a cash offer. You can close the deal in days and refinance later at your convenience.
3. Property Rehabilitations and Upgrades
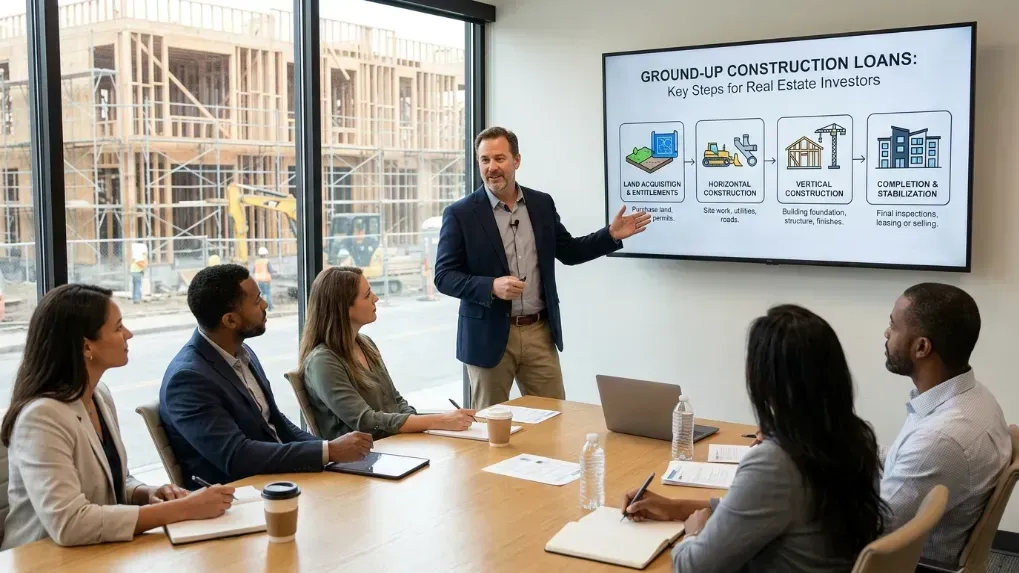
Distressed properties offer excellent profit margins. However, conventional lenders rarely finance homes needing major repairs. Private capital ignores minor cosmetic issues. Investors use these funds to buy the home and complete the renovations. If your project involves adding square footage, you might also consider our ground-up construction loans.
4. Stabilizing Rental Portfolios
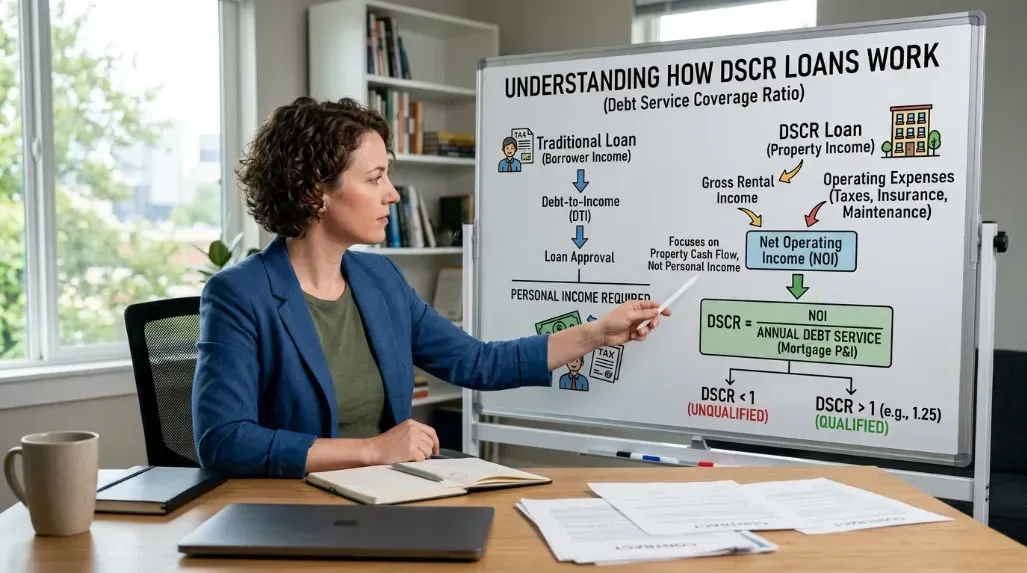
Landlords often purchase vacant multi-family units. These properties generate no income at purchase. A traditional bank will deny a loan for a vacant building. Short-term capital allows the buyer to acquire the property and place tenants. Once the property generates consistent rental income, the owner can refinance. For long-term rental holds, understanding how DSCR loans function is a critical next step.
Analyzing Short Term Real Estate Financing Options
Borrowers have several paths when seeking fast capital. Each loan type serves a distinct purpose. Choosing the right product maximizes your return on investment.
We have outlined the primary differences in the comparison table below.
| Loan Type | Typical Approval Speed | Standard Term Length | Primary Use Case |
|---|---|---|---|
| Bridge Loan | 5 to 10 Days | 6 to 24 Months | Transitioning between properties quickly. |
| Rehab Loan (Fix & Flip) | 5 to 14 Days | 6 to 12 Months | Buying and repairing distressed homes. |
| DSCR Loan | 15 to 30 Days | 30 Years | Financing stabilized, income-producing rentals. |
| Construction Loan | 14 to 30 Days | 12 to 24 Months | Building new structures from the ground up. |
Understanding this data helps you map out your investment timeline. Bridge capital clearly offers the fastest route to ownership. This speed compensates for slightly higher interest rates. The goal is to secure the property first. You can always arrange permanent financing later.
Planning a Successful Exit Strategy
Temporary loans require a clear exit plan. Private lenders want to know exactly how you will repay the principal. A well-defined exit strategy guarantees a smooth transaction for both parties.
The most common exit strategy is a standard property sale. Investors buy a home, fix the issues, and list it on the retail market. The proceeds from the sale pay off the loan balance. The investor keeps the remaining profit.
Refinancing is the second major exit path. Many buyers wish to keep the property as a permanent rental. Once the property is renovated and leased out, it qualifies for traditional or specialized rental financing. At this stage, borrowers frequently transition into our dedicated DSCR loans. This pays off the short-term debt and locks in a long-term rate.
Working with a Local San Diego Lending Partner
Real estate is inherently local. National lenders often misunderstand regional market nuances. A local lender grasps the true value of San Diego neighborhoods. We understand the difference between a property in La Jolla and one in El Cajon.
Working with a local team streamlines the entire process. Appraisals happen faster. Communication remains direct and transparent. Our team visits properties in person to assess their true potential. We base our lending decisions on local expertise and solid real estate fundamentals.
We operate directly from our headquarters at 356 Sunswept St, San Diego, CA. Having a physical presence allows us to serve our clients better. You can easily reach our office by calling 619-983-0898. If you want to know more about our background and methodology, take a moment to learn more about our local lending team.
You need a reliable partner to navigate complex property transitions. The right capital makes the difference between a missed opportunity and a profitable deal. Connect directly with HWH San Diego Hard Money Lender - Real Estate to discuss your next project.
Preparing Your Loan Application
Preparation prevents unnecessary delays. Private lending demands less paperwork than traditional banking. However, organizing your files speeds up the approval immensely.
First, clearly define the property details. Have the purchase contract ready. Know the exact address and the requested loan amount. Second, document your exit strategy. Decide whether you plan to sell or refinance. Write down your estimated timeline.
Next, prepare details regarding any required renovations. Provide a clear scope of work. Include cost estimates from licensed contractors. Lenders use this data to determine the after-repair value of the property. The higher the final value, the more capital you can access.
Finally, gather basic corporate documents if you purchase through an LLC. This protects your personal assets and simplifies the legal process. When your files are organized, it is time to take action. Please reach out to our funding specialists to begin the pre-approval phase.
Frequently Asked Questions
How fast can I secure a bridge loan in San Diego?
Private capital moves significantly faster than conventional financing. Assuming you provide all necessary property details, approvals often take just a few days. Funds can be dispersed and deals closed in as little as five to ten days.
Do bridge loans require high credit scores?
Hard money lenders prioritize the physical real estate asset over personal credit. While a decent credit history helps, it is not the deciding factor. The property value, the down payment, and your clear exit strategy hold much more weight during the approval process.
What happens when the bridge loan term ends?
These are short-term financial tools. Before the term expires, you must execute your exit strategy. You will either sell the property to pay off the balance or refinance the debt into a long-term conventional or DSCR loan.