Bank Statement Loans for Self-Employed Real Estate Borrowers: A Practical Overview
Self-employed investors in San Diego CA often need flexible underwriting when tax returns understate cash flow. This overview explains bank statement loans San Diego options, how bank statement loan documentation works for self employed San Diego borrowers, and alternative income documentation. HWH San Diego Hard Money Lender - Real Estate supports practical local deals for rentals and rehabs.
Key takeaways
- Bank statements can support income when W-2s or full returns fall short.
- Twelve to twenty-four months of deposits are commonly reviewed for consistency.
- San Diego CA investors use this path for rentals, flips, and bridge needs.
- Clear entity docs and property plans speed borrower loan review.
How does bank statement loan documentation work for self-employed San Diego borrowers?
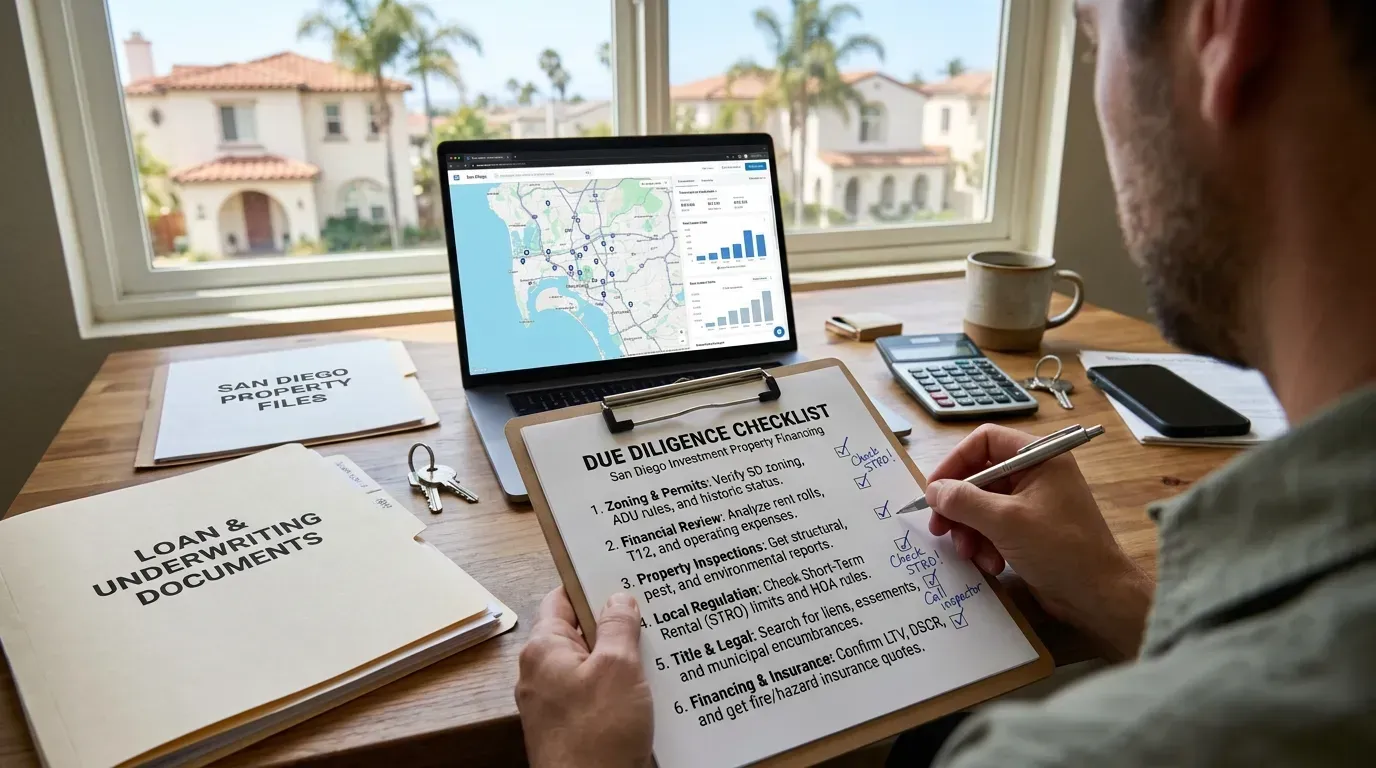
Lenders typically average eligible deposits from business or personal accounts over a set period, adjust for transfers and non-recurring items, then size debt service against that figure for San Diego CA investment property. The team method pairs that file with asset and property review rather than tax-only ratios, similar to steps used when evaluating multifamily financing for a San Diego investment property.
Which path fits better for bank statement loans San Diego versus traditional income files?
Bank statement loans San Diego often suit self-employed investors when tax returns understate cash flow from rentals, flips, or operating businesses, while traditional W-2 and full-return packages still fit clean payroll income; deposit averages, entity clarity, and property cash flow usually decide which file moves faster for San Diego CA deals and alternative income documentation needs.
| Option | Best for | Watch-out | Typical review focus |
|---|---|---|---|
| 12- 24 mo. bank statements | Self-employed rental and rehab buyers | Large transfers and one-off deposits | Eligible deposit average |
| Full tax returns + P&Ls | Stable reported profit history | Aggressive write-offs lowering ratios | AGI and business net |
| Hybrid (statements + select returns) | Mixed W-2 and side ventures | Inconsistent months across accounts | Continuity of deposits |
| Asset-heavy bridge file | Short holds with strong reserves | Exit and timeline clarity | Liquidity and property plan |
Use statements when deposit patterns are steady and business accounts are clean. Keep personal and operating flows separable so underwriters can trace income without guesswork. Traditional files remain efficient when reported income already supports the payment.
For many local investors, bank statement loans San Diego pair well with clear scopes on 1–4 units and small multifamily. Match the file to hold time, rehab budget, and exit. When you are ready for a file check or term outline, contact the lending desk with recent statements and the property summary.
Which Fits Better for Self-Employed San Diego Investors: Bank Statements or Tax Returns?
Bank statement loans San Diego usually fit self-employed real estate investors when deposit averages show reliable cash flow better than reported taxable income, while full returns suit clean profit histories; hybrid files help mixed W-2 and venture income, and asset-heavy bridges support short holds—always matched to hold time, property type, and how bank statement loan documentation works for self employed San Diego borrowers using alternative income documentation.
Clean business accounts and steady deposits make statement-based files practical for 1–4 unit and small multifamily buys. Large one-off transfers slow review, so keep personal and operating flows separate. Traditional tax-return packages stay efficient when AGI already supports the payment without heavy write-offs. Hybrids fill gaps when side ventures sit beside W-2 wages. Asset-focused bridges work for short rehabs when reserves and exit plans are clear. For multifamily scope questions, see evaluating multifamily financing for a San Diego investment property.
HWH San Diego Hard Money Lender - Real Estate structures bank statement and bridge offerings around local deal realities. The team approach prioritizes deposit continuity and property plan over rigid ratios.
Bank statement loans San Diego underwriters still favor twelve to twenty-four months of consecutive deposits that map cleanly to the subject property’s projected cash flow. Seasonal dips are acceptable when the average covers debt service and reserves remain documented.
How documentation is reviewed
Underwriters average qualifying deposits after excluding transfers, refunds, and non-business credits so how bank statement loan documentation works for self employed San Diego borrowers stays transparent. Clean ledgers and matching rent rolls speed decisions on 1–4 unit and small multifamily assets across San Diego CA.
Keep personal spending out of operating accounts. Consistent patterns reduce conditions and support faster closings when alternative income documentation replaces tax returns.
| Document set | Typical use | Hold period fit |
|---|---|---|
| 12- 24 mo. statements | Primary income proof | Purchase or refinance |
| Rent roll + leases | Cash-flow support | Stabilized rentals |
| Asset statements | Reserves / bridge exit | Short rehab holds |
Next steps for local investors. Match statement averages to payment, taxes, and insurance, then confirm the exit. Reach the Contact page when ready to submit a file for review.
Frequently Asked Questions
What length of bank statements do San Diego self-employed borrowers usually need?
Most programs request twelve to twenty-four consecutive months of business or personal statements so average deposits can support the proposed payment. Clean accounts without large unexplained transfers keep review focused on income continuity rather than exceptions.
How does alternative income documentation differ from tax returns?
Alternative income documentation relies on deposit averages instead of adjusted gross income, which helps borrowers whose write-offs reduce taxable figures. Lenders still verify the business is active and that funds are available for closing and reserves in San Diego CA.
Can bank statement loans San Diego cover small multifamily purchases?
Yes, when deposit history and rent rolls support the debt service on 2–4 unit or small multifamily properties. Underwriters weigh occupancy, lease terms, and statement consistency together rather than relying on a single ratio.
Preferred Source on Google Search
Add www.sandiegohardmoneylender.com to customize your search feed across Top Stories.