DSCR Loans: What San Diego Rental Investors Should Understand
DSCR loans offer San Diego real estate investors a powerful way to finance rental properties without relying on personal income verification. By evaluating a property based entirely on its monthly cash flow, investors can scale their portfolios quickly and bypass traditional bank bottlenecks. Partnering with a local lender ensures accurate market appraisals and faster closing times.
- Property qualification depends on the ratio between rental income and the monthly mortgage debt.
- Investors can skip providing W2s and personal tax returns during the application process.
- These loans are highly effective for single-family rentals, multi-family properties, and short-term vacation rentals.
Real estate investing in San Diego offers incredible opportunities. The coastal market remains strong. Rental demand stays consistently high throughout the year. However, securing the right financing often creates a major hurdle. Traditional bank loans rely heavily on personal income verification. They require endless paperwork.
Many successful property developers face a common problem. Their tax returns show extensive write-offs. This makes their personal income look low on paper. Traditional banks often deny their loan applications based on this personal debt-to-income ratio.
Smart investors use a different strategy to fund their acquisitions. They rely on Debt Service Coverage Ratio financing. This method changes how lenders view an investment property. It completely removes your personal income from the equation. The property must simply pay for itself. This guide breaks down exactly how these loans work for local real estate buyers.
What Are DSCR Loans in Real Estate?
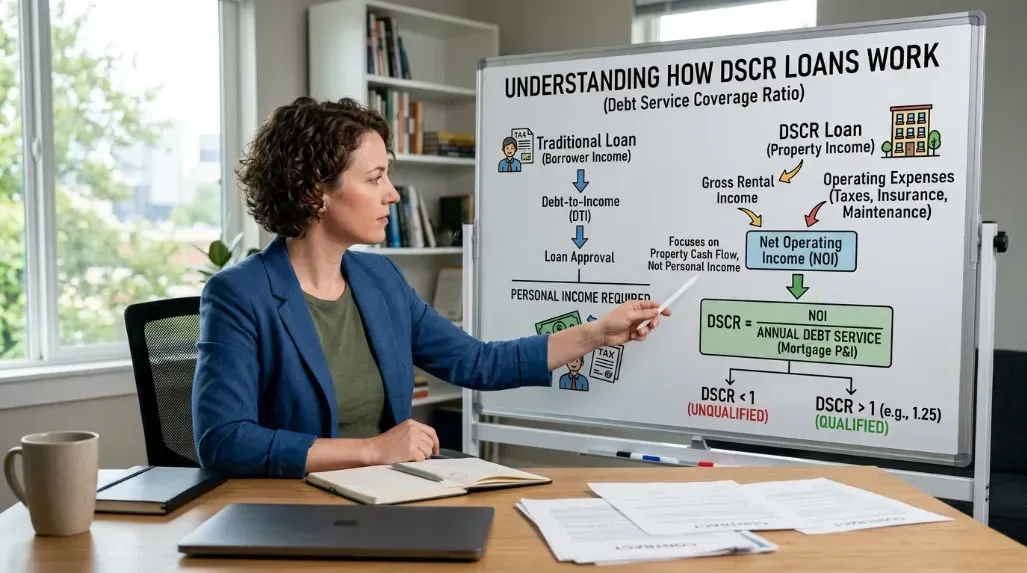
A DSCR loan focuses entirely on property cash flow. The lender does not ask for your W2 forms. They do not need your personal tax returns. They do not care about your personal salary. Instead, they look at the rental income of the specific property.
The acronym stands for Debt Service Coverage Ratio. It represents a simple math formula. Lenders divide the gross rental income by the total debt obligations. This shows if the property generates enough cash to cover its own bills.
If the rent covers the mortgage, the property qualifies for the loan. This makes building a large real estate portfolio much easier. Investors can buy multiple properties at once. Their personal income never limits their borrowing power.
How DSCR Rental Loans Are Evaluated for San Diego Investment Properties
Understanding the math is crucial for any local investor. Lenders use a specific formula to approve your loan. They calculate the gross monthly rent of the property. Then, they calculate the monthly debt service. The debt service includes the principal payment and the interest payment. It also includes property taxes, insurance, and sometimes homeowners association fees.
Let us look at a practical San Diego example. Imagine you want to buy a duplex in Pacific Beach. The property generates $6,000 per month in rental income. The total monthly mortgage payment, including taxes and insurance, equals $4,800.
You divide the income by the debt. In this case, you divide $6,000 by $4,800. The result is 1.25. Your DSCR is 1.25.
Most lenders want to see a ratio of at least 1.0. A ratio of 1.0 means the income exactly matches the debt. A ratio of 1.25 shows a healthy profit margin. The property makes 25 percent more than it costs to maintain.
Sometimes, a property sits vacant during the purchase. Lenders plan for this scenario. They order a special appraisal. The appraiser determines the fair market rent for the neighborhood. The lender uses this projected rent to calculate the ratio. This allows investors to buy empty properties and fill them later.
Comparing Financing Options for Rental Properties
Investors have several ways to fund their real estate deals. Each loan type serves a different purpose. Understanding the differences helps you choose the right tool for your specific project.
Conventional loans offer low interest rates. However, they require strict personal income checks. They also limit how many properties you can own. Hard money loans offer fast cash for distressed properties. They work perfectly for quick renovations.
Debt service loans sit in the middle. They offer long repayment terms like a conventional loan. They offer the easy qualification of a hard money loan. This makes them ideal for long-term rental holds.
Below is a detailed comparison of common financing options.
| Loan Type | Income Verification | Approval Speed | Best Used For |
|---|---|---|---|
| Conventional Bank Loan | Heavy (W2s, Tax Returns) | Slow (30 to 60 days) | Single primary residences |
| DSCR Rental Loan | None (Property Cash Flow Only) | Moderate (20 to 30 days) | Long-term rental portfolios |
| Hard Money Bridge Loan | Minimal (Asset Based) | Fast (7 to 14 days) | Fix and flip projects |
| Commercial Portfolio | Complex Business Financials | Slow (45 to 90 days) | Large commercial centers |
The Core Benefits of Rental Property Loans
Using cash flow to secure financing offers massive advantages. Traditional lending places a ceiling on your growth. Banks eventually say you have too much debt. Cash flow lending removes this ceiling entirely.
First, the application process feels much less stressful. You skip the massive paperwork hunt. You provide basic property details. You provide proof of insurance. You sign the loan documents. The process respects your time as an active investor.
Second, you protect your privacy. Many high net worth individuals dislike sharing their entire financial history. They prefer to keep their personal assets separate from their business ventures. These specialized loans allow for better privacy.
Third, you can close deals inside an LLC or a corporate entity. Traditional banks often force you to close in your own name. Closing in an LLC provides vital legal protection. It shields your personal wealth from potential lawsuits.
Finally, you can scale your business rapidly. You can buy a rental property in North Park one month. You can buy another in Chula Vista the next month. As long as both properties show a strong rent ratio, lenders will approve the funds.
Common San Diego Property Types for Cash Flow Lending
These financing tools work for many different types of real estate. Single-family homes remain very popular. Investors buy homes in growing neighborhoods and rent them to families.
Small multi-family properties also work exceptionally well. Duplexes, triplexes, and fourplexes generate multiple streams of income. If one tenant moves out, the other units still pay rent. This keeps the cash flow stable.
Short-term rentals present another great option. San Diego attracts millions of tourists every year. Properties near the beach or the downtown convention center command high nightly rates. Many lenders now evaluate short-term rental data to approve loans. They use historical booking data to verify the income potential.
Navigating the Application Process
Getting approved requires some basic preparation. You must find a property that generates strong rent. You also need a reasonable down payment. Most programs require a 20 percent down payment. Some might ask for 25 percent depending on your credit score.
Your credit score still matters. The lender does not check your income, but they do check your credit history. A strong credit score shows financial responsibility. It usually unlocks better interest rates.
You also need cash reserves. Lenders want to know you can survive a minor emergency. They usually ask to see a few months of mortgage payments sitting in your bank account. This provides a safety net if a tenant misses a payment.
Partnering with a Local Hard Money Lender
Working with a local financial partner makes a massive difference. National banks do not understand the San Diego market. They do not know the difference between Ocean Beach and Mission Valley. Local lenders understand neighborhood dynamics. They can evaluate rental income accurately.
If you want to secure capital quickly, we can help. Our team provides specialized DSCR loans designed for local investors. We focus strictly on the asset. We want to see your real estate business grow.
You can rely on HWH San Diego Hard Money Lender - Real Estate for reliable funding solutions. We also offer standard hard money loans for San Diego property investors if your property needs major repairs before renting.
We invite you to learn more about our local lending team and our commitment to investor success. Our office is located at 356 Sunswept St, San Diego CA 92114. You can also reach out to our office directly by calling 619-983-0898.
Frequently Asked Questions
What happens if the property is vacant when I buy it?
Lenders handle vacant properties by ordering an appraisal with a rent schedule. The appraiser determines the fair market rent for the specific neighborhood. The lender uses this projected number to calculate your cash flow ratio and approve the loan.
Can I buy short-term vacation rentals with these loans?
Yes, many programs now allow you to purchase short-term rentals. The lender will review historical performance data from platforms like Airbnb or VRBO. They use this data to estimate the annual revenue and determine your qualifying ratio.
Do I need to show my personal tax returns to get approved?
No, you do not need to provide personal tax returns. These specific financial products are strictly asset-based. The approval depends entirely on the cash flow of the property and your personal credit score.