Unlock Your Home’s Equity: A Clear Guide to Cash-Out Refinancing
Your home isn't just a place to live—it's a powerful financial tool. Unlocking your home’s equity through cash-out refinancing allows you to tap into your built-up property value for cash while securing a new mortgage. This process helps homeowners use their equity for various financial goals, such as paying off debt, renovating, or investing.
In cash-out refinancing, you replace your existing mortgage with a new one for more than you owe, and take the difference in cash. This can be a strategic move when done correctly. For homeowners with significant equity and strong credit, this option can unlock new opportunities and financial flexibility.
How Does Cash-Out Refinancing Differ from HELOCs or Home Equity Loans?
While cash-out refinancing, HELOCs (Home Equity Lines of Credit), and home equity loans all allow you to leverage your home’s value, they differ in structure and risk. A HELOC functions like a credit card with a revolving line, whereas a home equity loan is a second mortgage with fixed payments. Cash-out refinancing, however, replaces your current mortgage entirely—often extending your term or adjusting your rate.
This distinction matters. Unlike a second loan layered atop your existing mortgage, cash-out refinancing offers consolidation and possibly better interest rates, though it comes with closing costs and a more significant financial shift.
Why Home Equity Is a Powerful Financial Asset
Home equity is the difference between your home’s market value and your outstanding mortgage balance. As you pay down your loan and property values increase, so does your equity.
Tapping into this equity through a refinance allows you to turn static wealth into usable capital. Whether you’re upgrading your kitchen or consolidating debt, equity serves as a cushion—especially when borrowing responsibly.
Are You Eligible for Cash-Out Refinancing?
Eligibility depends on several factors, including how much equity you have and your financial health. Generally, lenders require that you retain 20% equity in your home after refinancing. So, if your home is worth $500,000, you’ll need to maintain at least $100,000 in equity post-refinance.
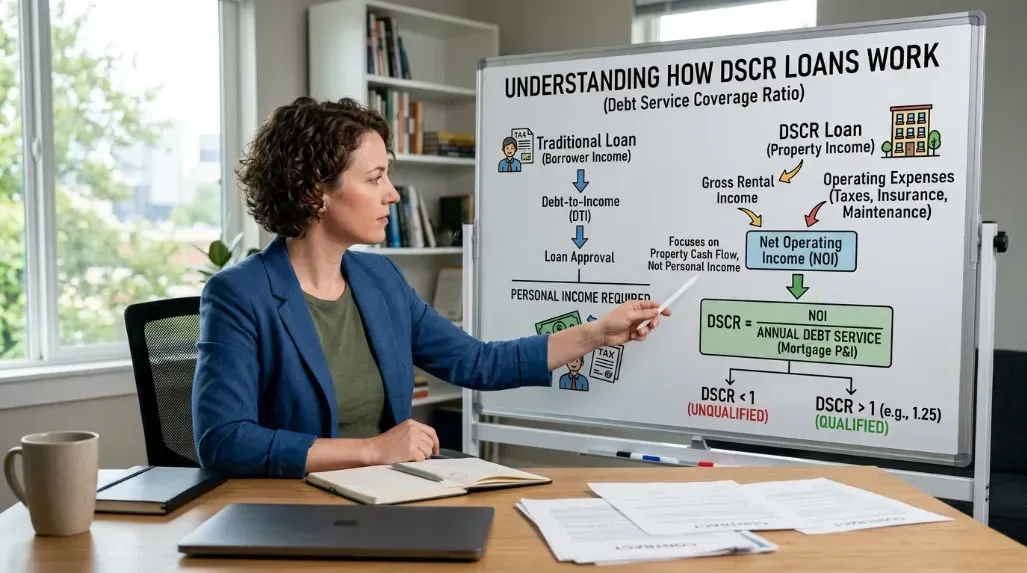
Lenders also assess your credit score, debt-to-income ratio, and employment history to determine your risk profile. If you’re self-employed or recently changed jobs, expect more scrutiny—but it’s not impossible to qualify.
Step-by-Step Cash-Out Refinancing Process
The process begins with evaluating your home's value, often through a professional appraisal. Then comes gathering documentation: tax returns, pay stubs, and statements. Next, you shop for lenders—both traditional banks and alternatives like a Hard Money Lender—who may offer quicker approval.
After selecting a lender, underwriting follows, then the closing. From start to finish, the process typically takes 30 to 45 days, though private lenders may move faster.
Top Benefits of Cash-Out Refinancing
Homeowners use cash-out refinancing for many goals, including:
- Home improvements that increase property value
- Debt consolidation at a lower interest rate
- Funding college education or medical expenses
- Launching a side business
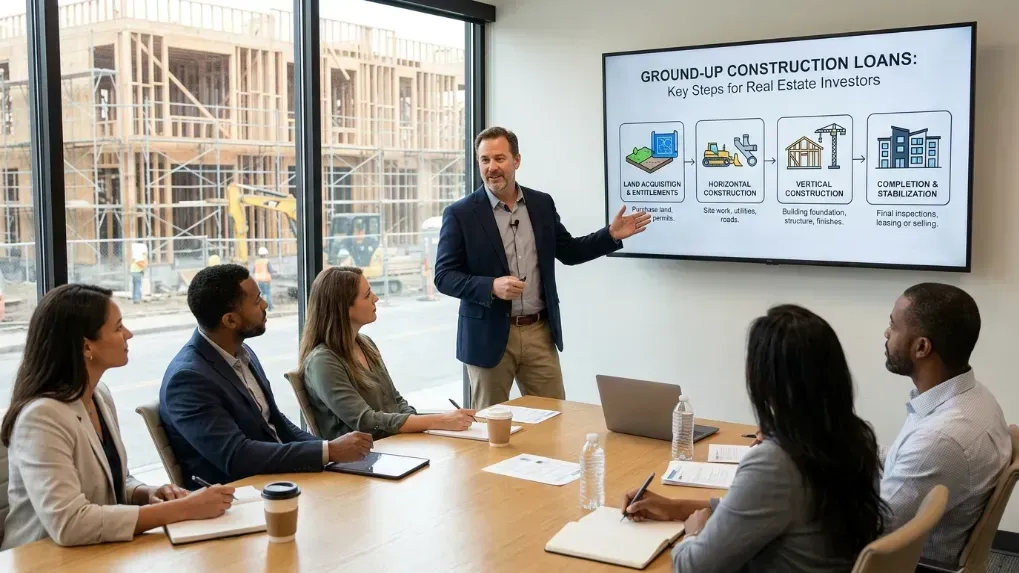
- Investing in real estate or other assets
Done wisely, it’s not just a cash grab—it’s a financial tool that can transform your future.
When Cash-Out Refinancing Might Not Be Right
Every financial product has a flip side. Refinancing can mean higher monthly payments or a longer loan term. In volatile markets, you might end up refinancing at a higher rate than your current one.
Additionally, overborrowing could put your home at risk, especially if your income changes or property values fall. It’s crucial to use the cash responsibly—avoiding short-term splurges in favor of long-term financial health.
Strategic Ways to Use Cash-Out Refinancing
Think of cash-out refinancing as an investment vehicle. Renovating a kitchen or bathroom can yield over 70% ROI. Consolidating debt at 6% interest vs. credit card debt at 20% is a no-brainer.
That said, use this money with intention and planning. Pay off your high-interest debts first. If you invest it, do so in appreciating or income-generating assets. Otherwise, you risk converting home equity into a depreciating purchase.
Regulations and Tax Implications to Know
While proceeds from cash-out refinances aren’t considered taxable income, interest deductibility on mortgage payments changes if the funds aren’t used for home improvements.
The IRS is watching, so talk to a tax professional. Also, understand that some loans may trigger private mortgage insurance (PMI) if your new LTV exceeds 80%.
Cash-Out Refinance Trends and Housing Market Outlook
As mortgage rates fluctuate, so does the popularity of cash-out refinancing. Recently, homeowners with low fixed rates have hesitated, but a shift in rates could make this strategy popular again.
Experts predict a resurgence in home equity borrowing as inflation pressures household budgets. Tools like Zillow, Redfin, and LendingTree offer calculators to assess your equity in real-time.
Unlock Your Home’s Equity
If you're sitting on home equity, you’re sitting on opportunity. Cash-out refinancing could unlock capital for investments, upgrades, or peace of mind. With proper planning, it’s one of the most flexible financial moves you can make.
For tailored advice, connect with a local expert today.
FAQs About Cash-Out Refinancing
What’s the typical timeline to complete a cash-out refinance?
Most refinances take between 30 to 45 days, depending on appraisal timing and document processing.
How much equity can I pull from my home?
Typically, lenders allow up to 80% of your home’s value, minus your current mortgage balance.
Will this affect my monthly mortgage payments?
Yes, your payment might go up if you borrow more or choose a shorter term—but sometimes it may drop if rates are lower.
Can I refinance again in the future?
Absolutely, but you must rebuild equity first, and rates or terms may differ.
How do I avoid scams in refinancing?
Stick with reputable lenders, get multiple offers, and never pay upfront fees without contracts.
What are alternatives if I’m not eligible?
Consider a HELOC, home equity loan, or speak with a
Hard Money Lender for more flexible criteria.
Next Steps: Making an Informed Financial Decision
Before diving into an application, review your financial goals. Use online calculators, gather quotes, and speak to professionals. If you're in a rush or traditional loans aren't an option, a Hard Money Lender may provide the speed and flexibility you need.
Don’t wait until equity opportunities pass you by—unlock your home’s financial potential today.
Links: