The Rise of Hard Money Loans: A Game-Changer in Real Estate Financing
Real estate is a fast-paced industry, and traditional lending often can’t keep up. That’s where hard money loans come into play. Once a niche funding method, hard money lending is now a mainstream solution for property investors and house flippers. This rise is no accident—fast approval times, asset-based lending, and fewer hoops to jump through make hard money loans a game-changer in modern real estate financing.
Hard money lenders are filling the gap left by traditional banks, offering flexible financing solutions when speed and opportunity matter most. As the industry evolves, understanding the ins and outs of hard money lending becomes essential for real estate professionals, investors, and developers alike.
What Are Hard Money Loans?
Hard money loans are short-term, asset-backed loans offered by private investors or companies. Unlike traditional loans that rely heavily on credit scores and borrower history, these loans are based mainly on the value of the property being used as collateral.
Hard money lenders evaluate deals differently. They focus on property potential rather than borrower reputation. This approach makes it possible for people with poor credit or unconventional income sources to get financed.
These loans are typically used for:
- Fix-and-flip projects
- Bridge financing
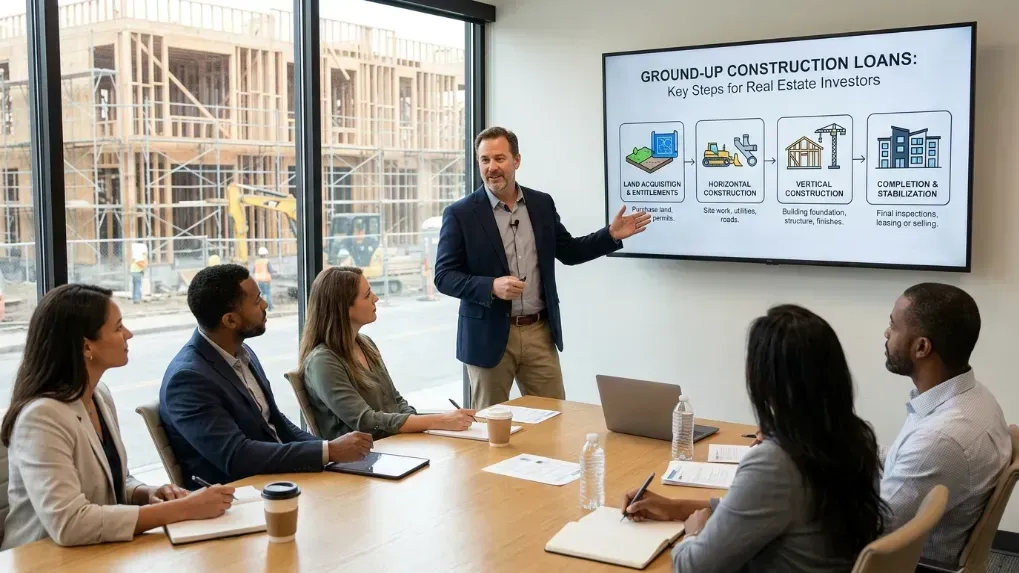
- Construction loans
- Land purchases
The rise of hard money loans reflects a growing demand for non-traditional lending options in a competitive, time-sensitive market.
Key Differences Between Hard Money and Traditional Loans
Understanding how hard money loans differ from traditional bank loans is crucial:
Criteria Hard Money Loans Traditional Loans
Approval Time 1–7 days 30–60 days
Credit Requirement Minimal Extensive
Loan Term 6–18 months 15–30 years
Interest Rates Higher (8–15%) Lower (3–6%)
Lender Type Private Institutional
While hard money loans may have higher interest rates, the speed and flexibility they offer make them ideal for time-sensitive deals.
Evolution of Real Estate Financing Over the Years
Traditionally, real estate financing was handled almost exclusively by banks. These institutions required extensive documentation, lengthy approval processes, and strong credit backgrounds. As the market evolved, so did the financing needs.
After the 2008 financial crisis, many banks tightened their lending policies. This shift opened doors for private lenders who could provide capital quickly and with fewer strings attached. Over time, this alternative lending method matured into a legitimate and vital part of the real estate financing landscape.
The Emergence of Hard Money Lending in the Real Estate World
The shift toward hard money lending began with savvy real estate investors. These individuals needed fast, reliable financing for flipping houses and seizing short-lived opportunities. As success stories piled up, more investors took notice.
Today, firms like Hard Money Lender offer structured, regulated services. They've brought professionalism to what was once considered a risky or shadowy corner of finance. These lenders now work hand-in-hand with seasoned investors, offering customized loan packages to meet specific project goals.
Why Real Estate Investors Are Turning to Hard Money Loans
Why are more investors ditching banks and heading straight to hard money lenders?
- Speed: Funding in days, not weeks.
- Fewer Requirements: No tax returns, W2s, or high credit scores needed.
- Asset-Based Lending: The property is the primary concern.
- Short-Term Focus: Ideal for fast-flip or rehab projects.
Real estate is about timing, and in hot markets, delays can kill deals. Hard money loans are helping investors act fast and stay competitive.
The Role of Speed and Flexibility in Real Estate Deals
Imagine finding a great investment property with multiple bidders. You need funds yesterday. Traditional lenders might take 30–60 days—by then, it’s gone. With a hard money loan, funding could arrive in 48 hours.
Flexibility is another win. Need creative structuring? Balloon payments? Interest-only options? Hard money lenders can often tailor deals to fit your timeline and your project needs.
How Hard Money Loans Work: The Basics
Here’s a basic breakdown of how a hard money loan is structured:
- Application: Simple form and a property appraisal.
- Approval: Based on the ARV (After Repair Value) of the property.
- Terms: Typically 6–18 months with interest-only monthly payments.
- Closing: Often within a week.
Lenders might fund up to 70% of the ARV, helping investors get in and out quickly with minimal personal risk.
Loan Terms, Interest Rates, and Collateral Requirements
Expect the following when working with a hard money lender:
- Interest Rates: 8% to 15%
- Loan-to-Value Ratio (LTV): Usually 60–75%
- Term Length: 6 to 18 months
- Collateral: Real property, often residential or commercial
These loans are often interest-only until the principal is paid in full at the end. Though costlier than traditional loans, their utility is unmatched for short-term goals.
Who Uses Hard Money Loans? Common Borrowers and Their Goals
Hard money isn’t just for flippers. Borrowers come from all walks:
- Real estate developers needing quick capital
- Buy-and-hold investors seeking bridge financing
- Contractors launching speculative builds
- Homeowners in urgent need of funds with poor credit
Each borrower uses hard money to seize time-sensitive opportunities that would be lost under conventional timelines.
Case Studies: Real-Life Success Stories in Real Estate Using Hard Money
Case 1:
John, a flipper in San Diego, secured a hard money loan in 72 hours and flipped a duplex within four months, netting a $60,000 profit.
Case 2:
Lena, a real estate agent turned developer, used hard money to fund three townhomes on undeveloped land. Without this flexible capital, the project would’ve remained a dream.
Such stories prove that the right lender can make or break your deal.
Benefits of Hard Money Loans for Real Estate Investors
- Quick Closings for auction and off-market deals
- Creative Structures that suit unconventional projects
- Minimal Paperwork, cutting down stress and delays
- Asset-Based Risk, reducing exposure to personal credit issues
These advantages can transform the way investors do business and scale their portfolios.
How Hard Money Loans Fuel Fix-and-Flip Projects
Hard money loans were practically made for the fix-and-flip model. Investors can:
- Buy undervalued homes
- Renovate quickly
- Sell fast at a profit
With loan terms built around quick exits, they reduce carrying costs and increase return on investment (ROI). No wonder flippers love them.
Understanding the Risks Involved in Hard Money Lending
Like all financial tools, hard money loans come with risks:
- Higher Interest Rates can erode profits if the project is delayed.
- Short Loan Terms mean pressure to finish fast.
- Default Risks can lead to property forfeiture.
It’s vital to have a clear exit strategy and stay on budget to minimize these risks.
When to Avoid a Hard Money Loan
Avoid these loans if:
- You lack a solid plan or exit strategy
- Your project timeline exceeds 18 months
- You’re unable to handle higher monthly payments
In such cases, a traditional loan might be safer.
The Economic Impact of Hard Money Lending on Local Markets
Hard money fuels revitalization in blighted neighborhoods. By providing fast capital, lenders help turn abandoned properties into livable homes—boosting local economies, creating jobs, and raising property values.
How Hard Money Lenders Shape Real Estate Trends
Lenders often spot emerging neighborhoods before they boom. By funding these deals, they help shape development trends and catalyze urban growth. Their capital turns plans into progress.
Are Hard Money Loans Legal and Ethical?
Yes—when done right. Hard money loans are regulated under state and federal lending laws, and ethical lenders provide transparent terms, fair rates, and legal contracts.
Current Regulations Governing Private Lending
Each state has its own licensing and interest rate limits. For example, California requires private lenders to follow the California Bureau of Real Estate and Department of Business Oversight rules.
Choosing the Right Hard Money Lender
A reputable lender should offer:
- Transparent terms
- Experience in your market
- Speedy closings
- Client testimonials
To explore more, visit this experienced Hard Money Lender.
Red Flags to Watch Out for When Selecting a Lender
- Vague or shifting loan terms
- No licensing or reviews
- Upfront fees before approval
- Lack of clear communication
When in doubt, always contact the lender to clarify details.
The Future of Hard Money Lending in Real Estate
With technology, regulation, and demand all evolving, hard money lending is set to become even more mainstream. Automated underwriting, AI-driven appraisals, and fintech partnerships will further streamline the process—making it even more appealing for tomorrow’s investors.
Frequently Asked Questions About Hard Money Loans
What is a hard money loan?
It’s a short-term, asset-based loan secured by real estate, typically offered by private lenders.
Is a hard money loan safe?
Yes, if you understand the terms and have a strong exit strategy.
Can I get a hard money loan with bad credit?
Yes. These loans focus on property value, not credit scores.
How fast can I get a hard money loan?
Funding can be completed in as little as 48–72 hours.
What are the interest rates for hard money loans?
Rates typically range from 8% to 15%, depending on the lender and risk level.
Can I use a hard money loan for personal needs?
No. They are generally used for real estate investment purposes only.
Final Thoughts: Is Hard Money Lending the Future of Real Estate Finance?
The rise of hard money loans has permanently altered the real estate financing game. In an industry where timing is everything, these loans offer unmatched speed, flexibility, and opportunity. While not for everyone, they are indispensable for investors who need to move fast.
With continued growth and innovation in the sector, hard money loans are no longer the backup plan—they're the new normal.
Links