Multi-Family Loans Made Simple: Everything You Need to Know
In the dynamic world of real estate investing, multi-family loans represent one of the most powerful tools for building long-term wealth. Whether you're a novice investor looking to buy your first duplex or a seasoned professional scaling your portfolio with a 20-unit apartment complex, understanding the nuances of financing can make or break your investment strategy.
Let’s break it all down. This article will be your comprehensive guide to multi-family loans, turning what seems complex into practical, actionable knowledge.
Understanding What Multi-Family Properties Are
Multi-family properties are residential buildings that house more than one family in separate units. These range from:
- Duplexes (2 units)
- Triplexes and fourplexes (3–4 units)
- Mid-size apartment buildings (5–50 units)
- Large multi-family complexes (50+ units)
Why do investors gravitate toward them? Because they provide consistent income, often qualify for special financing, and carry fewer risks than single-family rentals when it comes to vacancy.
The Appeal of Multi-Family Real Estate Investing
- Investing in multi-family real estate offers:
- Diversified income streams: Even if one tenant moves out, others remain to cover costs.
- Economies of scale: Repairs, property management, and renovations can be spread across more units.
- Tax benefits: Depreciation, mortgage interest deductions, and 1031 exchanges offer incredible advantages.
In short, it’s not just about passive income. It’s about smart financial growth.
Multi-Family Loans Made Simple
At its core, a multi-family loan is a mortgage used to finance a property with multiple rental units. These loans fall under both residential and commercial categories depending on the number of units:
- 2–4 units = Residential loans
- 5+ units = Commercial real estate loans
This distinction matters because it affects down payments, underwriting, and terms.
Types of Multi-Family Loans
FHA, VA, Conventional, Portfolio, and Hard Money—you’ll find many paths depending on your strategy. Here’s a breakdown:
Loan Type Best For Down Payment Key Requirement
FHA First-time buyers 3.5% Owner occupancy
VA Veterans 0% Military status
Conventional All investors 15–25% Good credit
Portfolio Niche borrowers 20–30% Relationship with lender
Hard Money Fast closings 25–40% Strong equity potential
Government-Backed Loan Options
FHA and VA loans are golden tickets for qualified buyers.
- FHA Loans: You can purchase up to a 4-unit building with only 3.5% down—if you live in one of the units.
- VA Loans: Exclusively for veterans, offering zero down payment on up to 4-unit homes with no mortgage insurance.
These programs are excellent entry points into multi-family investing.
Conventional Multi-Family Mortgages
These are offered by traditional lenders like banks and credit unions. You’ll usually need:
- 15–25% down
- Minimum credit score of 620
- Strong documentation
Interest rates are favorable, especially for investors with stellar credit histories.
Portfolio and Bank Loans
Unlike conventional loans, portfolio lenders keep the loans in-house rather than selling them. That means:
- More flexibility
- Custom underwriting
- Better terms for repeat borrowers
Local banks may approve unique deals that larger lenders would never touch.
Commercial Real Estate Loans Explained
For properties with 5+ units, commercial loans dominate. These often involve:
- Shorter terms (5–10 years)
- Higher down payments
- Balloon payments
That said, they also allow for larger acquisitions and higher loan amounts.
Hard Money Lenders: A Flexible Alternative
Need fast financing? Consider a Hard Money Lender. These private lenders focus less on credit and more on property value and exit strategy.
While rates are higher, the speed and flexibility they offer are unmatched—especially in competitive markets or when dealing with distressed properties.
Understanding Loan-to-Value (LTV) Ratios
LTV = Loan Amount ÷ Property Value
- Lower LTV = lower risk to lender
- Higher LTV = higher risk
Most lenders prefer an LTV of 75–80%, meaning you’ll need to put down 20–25%.
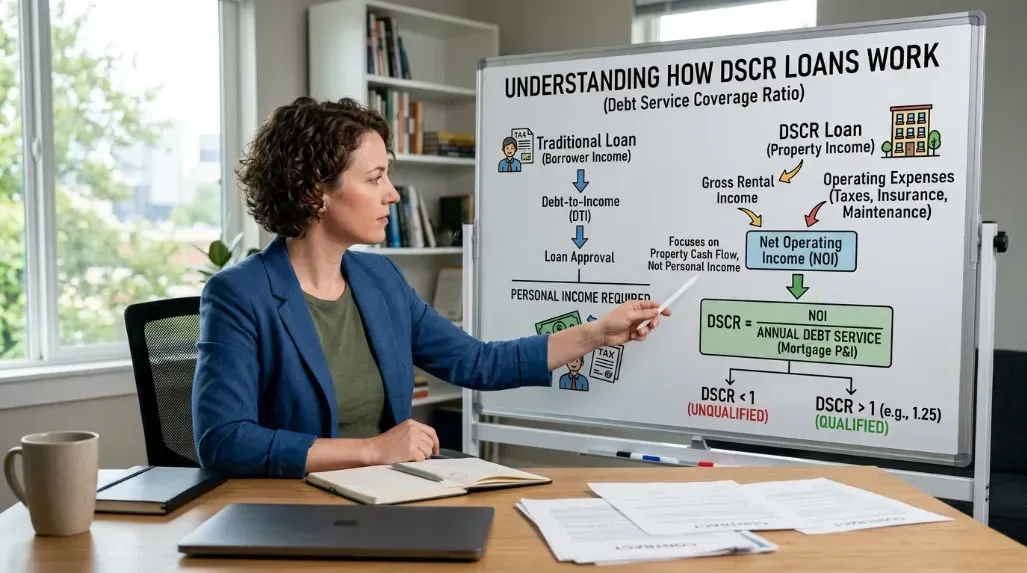
The Role of Debt Service Coverage Ratio (DSCR)
DSCR = Net Operating Income ÷ Debt Payments
A DSCR above 1.25 is considered safe. It tells lenders that the property earns more than enough to cover debt obligations, which is essential for approvals.
How Credit Score Impacts Loan Approval
Your credit score influences:
- Interest rate
- Loan approval
- Down payment requirements
A score above 700 opens the best doors. Below that, options narrow—but with creativity and strong income, you can still qualify.
Required Documentation for Loan Approval
You’ll typically need:
- Tax returns (2 years)
- W-2s or business financials
- Rent roll
- Property financial statements
- Personal financial statement
Being organized speeds things up dramatically.
Step-by-Step Loan Application Process
- Get Pre-approved
- Submit full documentation
- Get property appraisal
- Underwriting review
- Loan approval
- Close and fund
Each stage has its own timing and requirements. Be proactive!
Multi-Family Loan Terms to Know
- Amortization: Spreading payments over time
- Balloon Payment: Large final payment after interest-only period
- Interest-Only Period: Low early payments, higher later
These terms can drastically affect monthly cash flow.
Down Payments: What You Need to Know
Most loans require 15–30% down. But with FHA or VA, it could be far less. You can also use:
- Gift funds
- Partnerships
- Seller credits
How Interest Rates Are Determined
Interest rates vary based on:
- Market conditions
- Creditworthiness
- Loan type
Fixed vs. variable? Consider the risk. In uncertain times, fixed-rate loans offer stability.
Evaluating Multi-Family Property Cash Flow
Analyze:
- Gross rent
- Vacancy rate
- Expenses
- Net Operating Income (NOI)
- Cash-on-cash return
Use these numbers to decide if the loan supports sustainable profit.
Understanding the Appraisal Process
Multi-family appraisals consider:
- Income approach
- Sales comps
- Cost to build
Your loan approval hinges on the appraiser’s value.
The Impact of Market Conditions on Lending
Rising interest rates? Expect tighter loan terms. Cooling markets? Better deals.
Keep an eye on:
- Fed rate hikes
- Local inventory
- Rental demand
Working With Mortgage Brokers vs. Direct Lenders
Brokers: More options, but higher fees
Direct Lenders: Faster process, more control
Evaluate both before choosing your route.
How to Choose the Right Multi-Family Loan
Consider:
- Your timeline
- Your exit plan
- Your experience level
- The property’s income potential
Don’t just chase the lowest rate—chase the best structure.
Tips for First-Time Multi-Family Investors
- Live in one unit to access FHA financing
- Start small (2–4 units)
- Run the numbers carefully
- Network with local investors
- Get a mentor
Common Mistakes to Avoid With Multi-Family Loans
- Over-leveraging
- Ignoring repairs and maintenance
- Underestimating expenses
- Choosing the wrong loan structure
- Failing to plan for vacancies
Refinancing Multi-Family Loans
Reasons to refinance:
- Lower rates
- Cash-out equity
- Better terms
- Debt consolidation
Check your DSCR and LTV to see if you qualify.
Exit Strategies and Loan Repayment Planning
Options include:
- Sell and 1031 exchange
- Refinance and hold
- Pay down debt and create equity
Match your loan term with your plan.
Case Study: Successful Use of Multi-Family Loans
Sarah, a nurse from California, used an FHA loan to purchase a triplex in San Diego. She lived in one unit, rented the other two, and covered her mortgage. Three years later, she refinanced, bought another property, and now owns 10 units—all financed through strategic lending and partnerships with a local Hard Money Lender.
Contact a Local Loan Specialist Today
Ready to start your multi-family investing journey? Speak with a seasoned pro—visit the Contact Page to get personalized advice.
Frequently Asked Questions About Multi-Family Loans
Can I buy a multi-family property with no money down?
Yes, through VA loans if you're a veteran. FHA loans also offer low-down payment options.
What credit score do I need for a multi-family loan?
Most lenders require at least 620. Higher scores unlock better rates.
Is owner-occupancy required for all multi-family loans?
No. Only FHA and VA require it. Conventional and commercial loans don’t.
Can I refinance a multi-family loan later?
Absolutely. You can lower your rate, change terms, or access equity.
How is loan approval different for commercial vs. residential multi-family?
Commercial loans are based more on the property’s income than your personal income.
Is using a hard money lender safe?
It is—if you understand the terms. Ideal for quick deals or fix-and-flips.
Conclusion: Is a Multi-Family Loan Right for You?
If you’re serious about building wealth through real estate, multi-family loans are your secret weapon. They unlock more doors—literally and figuratively—than single-family investing ever could.
Whether you’re a beginner with one unit in mind or a pro planning a 20-unit portfolio, mastering this financing strategy is your first step toward lasting success.
Links: