Exploring Your Options: Commercial Real Estate Loans in San Diego
In the dynamic and ever-evolving real estate landscape of Southern California, commercial real estate loans in San Diego offer investors, developers, and entrepreneurs a gateway to lucrative opportunities. Whether you're acquiring office buildings downtown or renovating a retail space in Hillcrest, financing is a crucial part of the equation. With diverse lending options available, navigating this terrain requires both insight and strategy.
San Diego’s commercial real estate scene is vibrant yet competitive. Hence, understanding your financing options is more than just a smart move—it’s essential. In this article, we’ll explore every aspect of commercial real estate loans in San Diego, tailored to help you make informed and confident decisions.
Understanding Commercial Real Estate Loans
Commercial real estate (CRE) loans are a category of mortgage designed specifically for financing income-producing properties. Unlike residential loans, these are typically used to purchase or renovate properties like office buildings, industrial warehouses, retail shopping centers, and multifamily apartments with five or more units.
These loans are often structured around the income potential of the property, and they carry different underwriting criteria compared to traditional mortgages. This makes them more complex but also tailored to high-reward ventures.
Key Differences Between Residential and Commercial Loans
At first glance, both residential and commercial loans may seem similar—they both involve borrowing money to acquire property. However, the differences are significant:
- Term lengths: Residential loans typically offer 15–30 year terms, while commercial loans may range from 5–20 years.
- Amortization: Many commercial loans are not fully amortized, meaning a balloon payment is required at the end.
- Approval process: Commercial loans consider the property's income potential rather than just the borrower's income.
This complexity underscores the need for proper planning and expert advice.
The Role of Credit Scores and Financials in CRE Loans
Just like in residential lending, creditworthiness is important in commercial real estate loans. But here, lenders are also concerned with:
- Business credit scores (if applicable)
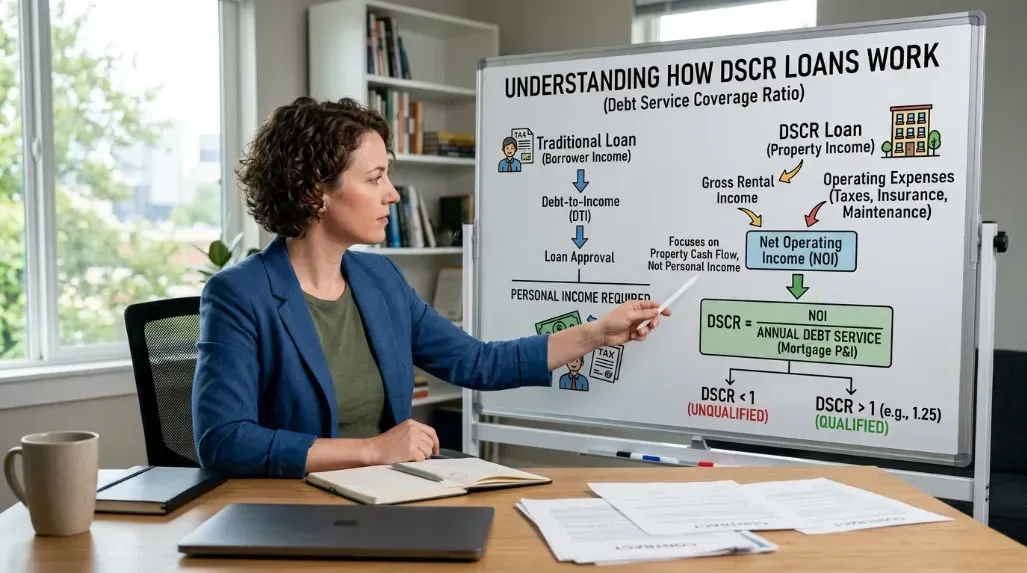
- Debt-service coverage ratio (DSCR)
- Income statements and cash flow projections
A well-prepared financial package can increase your chances of approval significantly.
Types of Properties Eligible for CRE Loans
Commercial loans in San Diego cover a wide range of property types:
- Office buildings in downtown or Sorrento Valley
- Retail spaces in Gaslamp Quarter
- Industrial properties in Otay Mesa
- Mixed-use buildings in University Heights
- Multifamily apartments in North Park
Different properties may come with different risk profiles, influencing the terms and conditions of the loan.
How Loan-to-Value (LTV) Impacts Approval
The Loan-to-Value (LTV) ratio is a key metric in commercial lending. It measures the loan amount against the appraised value of the property. A typical LTV in CRE loans falls between 65% and 80%. Lower LTVs reduce risk for lenders and often lead to better interest rates.
Traditional Bank Loans for Commercial Real Estate
Local and national banks are primary sources for CRE loans. These loans come with competitive interest rates and longer terms. However, they often involve stricter underwriting, longer processing times, and more documentation requirements.
Banks like Wells Fargo, Chase, and local players such as California Bank & Trust frequently provide CRE financing in San Diego.
SBA 504 vs. SBA 7(a): Which One Is Best?
Small Business Administration loans offer fantastic opportunities for business owners:
- SBA 504: Ideal for purchasing owner-occupied commercial real estate. Offers low fixed rates and long repayment terms.
- SBA 7(a): More flexible; can be used for property purchases, renovations, or working capital.
Choosing between them depends on your business needs and long-term goals.
Bridge Loans: A Short-Term Solution
Bridge loans are short-term loans used to "bridge" the gap between transactions or to secure quick financing while waiting for longer-term funding. They are useful in competitive real estate markets like San Diego where time is often of the essence.
Construction Loans for Commercial Projects
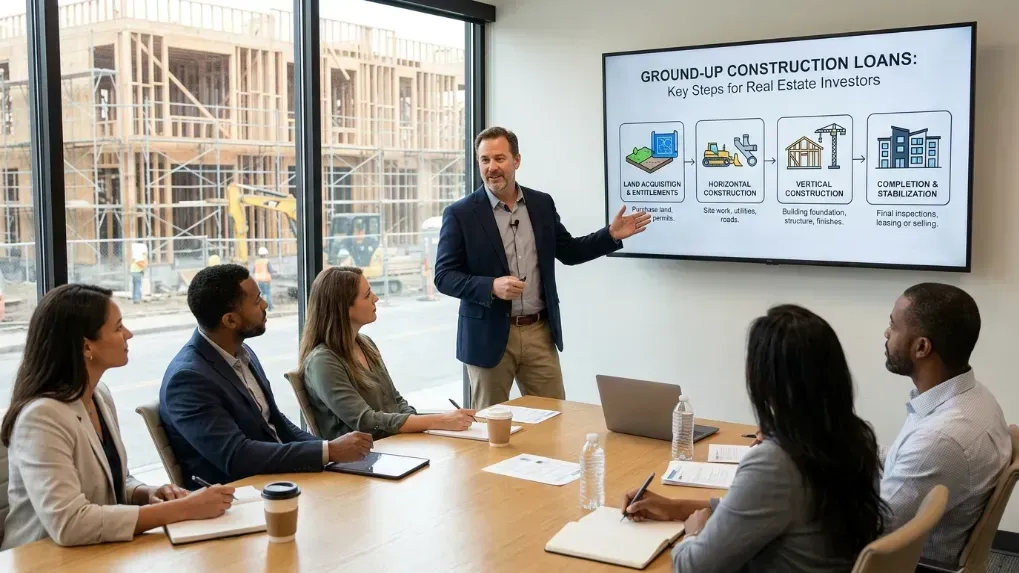
Planning a new development in Mission Valley or Pacific Beach? A construction loan offers phased funding based on project progress. These loans are complex and require detailed construction plans, contractor agreements, and permits.
Hard Money Loans in San Diego
For those who need fast funding with less red tape, a Hard Money Lender in San Diego can be a game changer. These loans are asset-based and ideal for investors seeking quick acquisitions, flips, or short-term projects. Interest rates are typically higher, but the speed and flexibility often outweigh the costs.
Mezzanine Financing: What You Need to Know
Mezzanine loans act as a hybrid between debt and equity financing. Common in large-scale commercial projects, this option allows borrowers to secure additional funds by offering equity stakes. It's higher risk but can unlock significant capital.
Choosing a Commercial Real Estate Lender in San Diego
The right lender can make or break your investment. When vetting potential lenders, consider:
- Their knowledge of the local market
- Flexibility of loan terms
- Reputation and transparency
Whether you're working with a bank, credit union, or Hard Money Lender, ensure their services align with your goals.
Why Local Knowledge Matters in CRE Lending
A lender who understands the San Diego market can provide better guidance, quicker appraisals, and more accurate risk assessments. Local lenders may also offer in-house decision-making, reducing red tape.
How to Compare Loan Offers Effectively
Before signing any agreement:
- Review the APR, not just the interest rate
- Ask about prepayment penalties
- Evaluate amortization schedules
- Check closing costs and fees
Never hesitate to request clarification or shop around for better terms.
Working With a Hard Money Lender
Need fast funding or have a property that doesn’t qualify for conventional loans? Reach out via the Contact page of a trusted San Diego hard money lender. Many investors use these short-term loans to gain a competitive edge in the bidding process.
What Lenders Want: Loan Documentation Checklist
To expedite approval, prepare the following:
- Business and personal tax returns (2–3 years)
- Property appraisals
- Rent rolls and lease agreements (for investment properties)
- Business plan (if applicable)
- Environmental assessments
- Credit reports
Proper documentation shows professionalism and preparedness.
How to Prepare a Winning Loan Application
Lenders want to minimize risk. You can stand out by:
- Showing strong cash flow
- Offering higher down payments
- Backing your claims with data
- Including professional valuations and feasibility studies
A detailed and honest approach always works better than glossing over potential issues.
Navigating Pre-Approvals and Underwriting
Getting pre-approved gives you leverage during negotiations. Once your application is submitted, the underwriting phase begins, where every detail is scrutinized. This stage may involve site visits, credit checks, and property evaluations.
Understanding Interest Rates and Amortization
Commercial loan interest rates are influenced by:
- Loan term
- Creditworthiness
- Property type
- Federal Reserve benchmarks
Amortization can range from 10 to 25 years, and many CRE loans are not fully amortized, requiring balloon payments.
Typical Terms and Conditions for CRE Loans
Expect these standard terms:
- Down payments: 20%–35%
- Fixed or variable interest rates
- Prepayment penalties
- Term limits: 5–20 years
- DSCR: 1.20 or higher
Always read the fine print before committing.
Hidden Fees and How to Avoid Them
Watch out for:
- Origination fees
- Processing fees
- Legal costs
- Appraisal and inspection fees
Request a detailed Loan Estimate and compare it with the Closing Disclosure. Transparency is key.
Common Pitfalls in Commercial Loan Applications
Avoid these mistakes:
- Submitting incomplete documentation
- Overestimating income projections
- Underestimating operational costs
- Ignoring zoning and code compliance
Avoiding these can dramatically improve your approval chances.
How to Increase Approval Odds
Boost your odds by:
- Partnering with a co-borrower
- Offering additional collateral
- Strengthening your business profile
- Reducing debt-to-income ratio
A lender is more inclined to approve a borrower who presents fewer risks.
Exit Strategies for Commercial Property Loans
Have a plan for loan repayment. Common exit strategies include:
- Refinancing
- Selling the property
- Utilizing rental income
- Paying off with business revenue
A clear exit plan gives lenders confidence in your repayment ability.
Legal Considerations in CRE Financing
Commercial loans often involve:
- Title insurance
- Personal guarantees
- Environmental due diligence (Phase I & II)
- Zoning and land use approvals
Always consult a real estate attorney to avoid future surprises.
Tax Benefits of Owning Commercial Property
Commercial property ownership comes with tax perks:
- Depreciation deductions
- Mortgage interest deductions
- 1031 exchanges for tax deferral
A savvy tax strategy can save you thousands annually.
Expert Tips for First-Time Commercial Real Estate Borrowers
- Start small; consider multifamily or mixed-use buildings
- Build relationships with lenders early
- Keep reserves for unexpected expenses
- Learn from experienced investors
Education and caution are the best allies for newcomers.
Building Relationships With Lenders
In commercial real estate, relationships matter. Lenders are more likely to accommodate clients they trust. Stay in touch, keep them updated, and always honor your commitments.
FAQs About Commercial Real Estate Loans in San Diego
What’s the minimum credit score needed?
Typically, lenders prefer scores above 660, though alternative lenders may be more flexible.
Can I get a commercial loan with no experience?
Yes, especially if you partner with experienced investors or offer strong financials.
How long does approval take?
From application to funding, it can take anywhere from 30 to 90 days, depending on the lender and loan complexity.
Are down payments negotiable?
Sometimes, especially if you offer additional collateral or a strong business plan.
Do commercial loans offer fixed rates?
Yes, both fixed and adjustable-rate options are available, depending on the lender and loan type.
Can I use a commercial loan for a residential rental property?
Only if it’s a multifamily building with five or more units; otherwise, a residential investment loan is more appropriate.
Final Thoughts on Exploring Commercial Real Estate Loan Options
Navigating the world of commercial real estate loans in San Diego may seem overwhelming at first, but armed with the right knowledge and partners, it becomes a strategic journey toward wealth creation. San Diego’s diverse neighborhoods offer rich investment opportunities, and understanding your financing options is the first step toward capitalizing on them.
Whether you’re eyeing a high-rise office, converting a warehouse, or launching your own retail hub, the right loan can make all the difference. Take your time, consult professionals, and don’t hesitate to explore non-traditional avenues such as Hard Money Lending to unlock fast, flexible financing.
Links: