Key Facts About Fix and Flip Hard Money Loan for Real Estate Success
A fix and flip hard money loan is a short-term, asset-based loan used by real estate investors to purchase and renovate properties quickly for resale. Unlike conventional mortgages, these loans are funded by private investors or companies, commonly known as hard money lenders, who evaluate the deal based on the property's value—particularly the After Repair Value (ARV)—rather than the borrower’s credit score or income history.
This financing option is essential for flippers who need to move fast in competitive markets. These loans typically carry higher interest rates and shorter terms but offer unmatched speed and flexibility. It’s no wonder many investors prefer this route over the traditional lending maze.
The Rise of Fix and Flip Real Estate
In recent years, television shows, real estate influencers, and online flipping courses have spotlighted the lucrative world of flipping houses. This exposure has opened the door for a new wave of real estate entrepreneurs seeking quick returns. However, flipping a property successfully hinges heavily on access to fast capital—enter the fix and flip hard money loan.
Whether you're restoring a 1920s bungalow or gutting a suburban ranch home, these loans provide the liquidity you need to act swiftly and outbid slower, conventional buyers.
Why Hard Money Is Perfect for Flipping Houses
Let’s face it—banks move slow. When you’re eyeing a hot deal, you don’t have 45+ days for underwriting to give you the green light. A fix and flip hard money loan is often approved within a few days.
Here’s why it works:
- Minimal documentation
- Loan decisions based on property potential, not personal finances
- Quick funding—sometimes within 3-7 days
- No red tape: skip the credit checks and lengthy appraisals
This means more deals, more flips, and more profits.
Difference Between Hard Money and Traditional Loans
Traditional bank loans are like cargo ships—slow and steady. Hard money loans? Think speedboats. Here’s a quick breakdown:
Criteria Hard Money Loan Traditional Loan
Approval Time 1–7 days 30–60 days
Basis for Approval Property value (ARV) Credit, income, DTI ratios
Documentation Needed Minimal Extensive
Flexibility High Low
Term Length 6–18 months 15–30 years
Ideal For House flipping, quick closes Long-term residence
How Fix and Flip Hard Money Loans Work in Practice
Let’s walk through it. You find a distressed property listed below market value. You estimate that with $50,000 in renovations, it could sell for $250,000. A hard money lender may lend you 70% of the ARV—around $175,000.
- Purchase Price: $120,000
- Rehab Budget: $50,000
- Total Investment: $170,000
- Potential Loan: $175,000
Boom—you’re funded. You close fast, renovate quickly, and list the property for sale. Within months, you’ve turned a tidy profit—all made possible through a hard money loan.
Key Players: Borrowers, Lenders, and Brokers
- Borrowers: Real estate investors seeking fast financing.
- Hard Money Lenders: Like this one in San Diego, private institutions or individuals funding the loan.
- Brokers: Middlemen who connect borrowers with lenders (optional).
Each party plays a crucial role, but a trustworthy lender is the cornerstone of a successful flip.
Loan Terms You Should Expect
Most fix and flip hard money loans come with:
- Term Length: 6–18 months
- Interest Rate: 8%–15%
- Origination Fees (Points): 2%–5%
- Repayment: Interest-only with balloon payment
Understanding these terms ensures you don’t get caught off guard mid-project.
Interest Rates and Points: What You Pay
Yes, these loans are expensive—but for good reason. Lenders are taking on significant risk. Here's an example:
- Loan Amount: $150,000
- Interest Rate: 12%
- Points: 3 (or $4,500)
Monthly payments are typically interest-only, so you'd pay $1,500 per month until the balloon payoff.
Understanding Loan-to-Value (LTV) and After Repair Value (ARV)
LTV is the ratio of the loan amount to the property's current value. ARV is the projected market value post-renovation.
Lenders base your loan on a % of the ARV (usually 65–75%). It’s vital you accurately estimate ARV with comps and contractor quotes.
Top Advantages of Using Fix and Flip Hard Money Loans
- Speed: Secure funds in days, not weeks.
- Flexibility: Credit isn’t a dealbreaker.
- Scalability: Fund multiple deals simultaneously.
- Opportunity Access: Compete with cash buyers.
You can’t scale fast using traditional lending. With hard money, the pace is in your hands.
Speed and Simplicity of Approval
You’ll usually need:
- Purchase contract
- Rehab budget
- Exit strategy
- Some proof of experience (if you're not a first-timer)
And that’s it—forget the tax returns and 700+ FICO scores.
Flexible Underwriting Criteria
Unlike banks, hard money lenders focus on:
- Property deal structure
- ARV and exit plan
- Experience level (optional)
Some lenders even offer first-time flipper programs.
Ideal for Time-Sensitive Deals
Found a foreclosure or short sale with a deadline? Hard money is your go-to. You’ll beat out slower buyers every time.
Risks and Drawbacks to Be Aware Of
While powerful, these loans aren’t risk-free.
- High interest: Double or triple that of traditional loans
- Short terms: Missed deadlines can trigger foreclosure
- LTV limits: You may need 10–20% down
- Exit risk: If the flip doesn’t sell, you’re still on the hook
Preparation and strong project management are your shields.
Steps to Apply for a Fix and Flip Hard Money Loan
The application process is swift but strategic.
- Identify the Property – Have a signed purchase contract ready.
- Prepare a Rehab Scope – Include material/labor estimates and a timeline.
- Submit to a Hard Money Lender – Use a trusted Hard Money Lender.
- Get a Term Sheet – Review loan terms and submit final docs.
- Close Fast – Most lenders fund within 7–10 days.
What Lenders Look For
- Deal profitability
- Location desirability
- Borrower experience
- Clear exit plan
The better the deal, the more lenient the lender may be.
Documents and Paperwork Needed
Be ready with:
- Property appraisal or comps
- Rehab budget and timeline
- Entity documentation (LLC articles, EIN)
- Insurance quotes
Mistakes That Could Cost You the Deal
- Overestimating ARV
- Underestimating rehab costs
- Missing deadlines
- Poor communication with the lender
Be realistic and proactive. Transparency builds trust and credibility.
When Should You Use Hard Money for House Flipping?
Use it when:
- The deal requires fast funding
- The property condition disqualifies traditional loans
- You’re short on liquidity but have equity or a partner
Avoid it if:
- The margins are razor thin
- You’re unsure of your exit strategy
Fix and Flip vs. Buy and Hold Loans
Buy-and-hold investors prefer long-term rental loans. Hard money, in contrast, is designed for short bursts of high-profit work.
Purpose Fix & Flip Buy & Hold
Term Length 6–12 months 15–30 years
Speed Needed Immediate Not always critical
Strategy Renovate + Sell Renovate + Rent
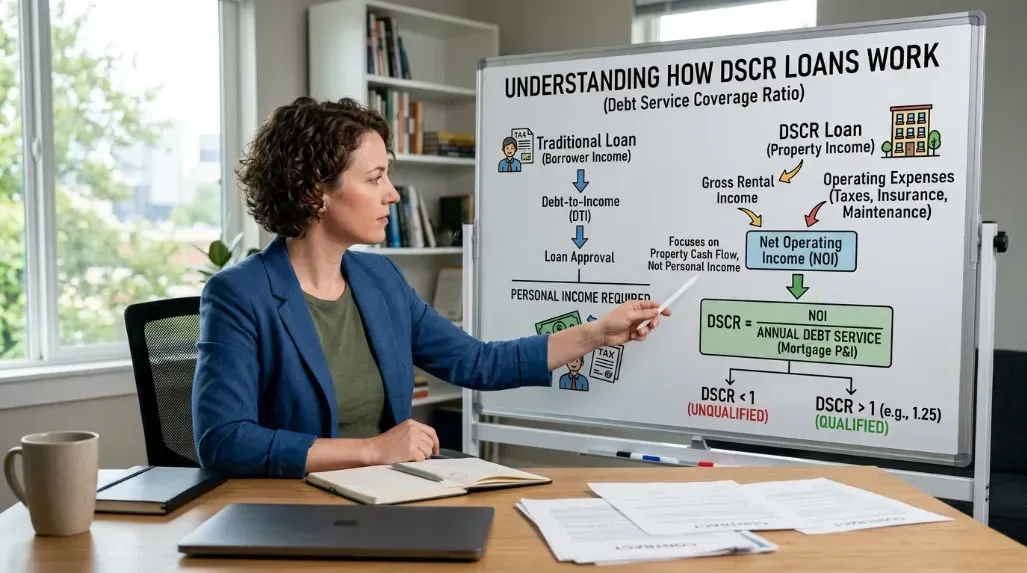
Loan Type Hard Money Conventional/DSCR
How Seasoned Investors Use These Loans
Experienced flippers stack projects using multiple loans. By building relationships with lenders, they unlock better rates, lower points, and flexible repayment structures.
Real Fix and Flip Loan Success Stories
Case Study: The Foreclosure Flip
Investor Jill found a bank-owned duplex listed at $190K. With $45K in renovations and a projected ARV of $300K, she secured $210K through hard money, flipped it in 4 months, and walked away with a $45K profit.
Case Study: Beating the Clock
Tom had 7 days to close on an estate sale. A hard money lender funded $250K in 4 days. Post-rehab, the property resold in 6 weeks—netting $60K profit.
Legal Considerations for Fix and Flip Loans
Each state has lending laws. Some require lender licensing; others set max interest rates. Consult a real estate attorney before signing.
Ensure:
- You’re operating through a legal entity (LLC)
- Your lender complies with state law
- You understand foreclosure clauses
How to Choose the Right Hard Money Lender
Vet your lender thoroughly. Ask:
- Are you direct or a broker?
- What are your rates and points?
- Is there a prepayment penalty?
- Can you close in less than a week?
Use a trusted, experienced Hard Money Lender for peace of mind.
Why San Diego Is a Prime Market for Fix and Flip
San Diego’s real estate is hot. Inventory is limited, and property values are rising.
Top Features:
- Distressed properties in older neighborhoods
- High ARV potential
- Favorable year-round construction climate
Flippers thrive in areas like North Park, Chula Vista, and City Heights.
Tips for Maximizing ROI with Hard Money Loans
- Use contractor bids to refine your budget
- Build lender relationships for better terms
- Always overestimate your timeline and costs
- Sell fast to avoid holding costs
Time is literally money.
FAQs About Fix and Flip Hard Money Loans
What credit score do I need?
Often none. These loans focus on the asset, not your credit.
Can I get 100% financing?
Only if you have strong experience and a stellar deal. Most require 10–20% down.
What happens if I can’t sell in time?
Refinance or extend the loan, but expect penalties or fees.
Do I need to flip under an LLC?
Yes, most lenders only work with business entities.
How fast can I close?
Some lenders can fund in as little as 3 days.
Can I use hard money for rental properties?
You can use it to acquire and renovate, then refinance into a rental loan.
Ready to Get Started?
If you're ready to dive into the world of real estate flipping, don't wait. Reach out to a trusted hard money lender today to secure your next investment opportunity.
Links: