Everything You Need to Know About Construction Loans
Building your dream home from the ground up is a thrilling journey, but it comes with a complex set of financial steps. Unlike standard mortgages, construction loans are short-term, specialized lending tools designed to finance the building of a home. They involve higher scrutiny, structured disbursement of funds, and more direct lender involvement.
So, if you're envisioning a new build or a major renovation, understanding how construction loans work is crucial. This guide covers everything you need to know about construction loans, so you can break ground with confidence.
How It Differs From Regular Home Loans
A traditional mortgage releases the full loan amount at once to the seller. A construction loan, however, releases money in stages—also known as “draws”—based on project milestones. Additionally, you usually only pay interest during the construction phase, and the full repayment begins once the build is complete or rolled into a permanent loan.
Draw Schedules and Project Milestones
The bank doesn't just give you a lump sum. Instead, your loan will have a draw schedule tied to milestones like site prep, foundation laying, framing, plumbing, and final inspection. Each phase requires lender approval before funds are released, protecting both borrower and lender from potential misuse.
One-Time Close, Two-Time Close, Renovation Loans
There are several types of construction loans:
- One-Time Close Loans: Combine construction financing and a mortgage into one loan.
- Two-Time Close Loans: Separate closing processes—first for construction, then a second for permanent financing.
- Renovation Loans: Perfect for major remodels or flipping existing structures.
Each has its pros and cons depending on your financial situation and project scale.
From Homeowners to Developers
Who are construction loans for? Not just new homeowners. These loans also benefit:
- Real estate investors
- Homebuilders
- Commercial developers
- Landowners building custom homes
Whether you're a first-time builder or an experienced investor, there's a construction loan that fits your needs.
A Side-by-Side Comparison
Feature Construction Loan Traditional Mortgage
Funds Disbursement In stages (draw schedule) Lump sum
Loan Duration 6-24 months 15-30 years
Interest Rate Variable (usually higher) Fixed or variable
Use Case New builds, renovations Purchasing existing homes
Qualification Difficulty More complex Simpler (less paperwork)
Land, Labor, Permits, and More
A construction loan can cover almost every component of your building process:
- Land purchase
- Architecture and design
- Building materials
- Contractor labor
- Permits and inspection fees
- Utility installation
- Landscaping (in some cases)
Borrower, Builder, and Lender
Each construction loan involves three key parties:
- Borrower: Provides vision, credit, and often a down payment.
- Builder: Must be licensed and insured, with a track record.
- Lender: Evaluates plans, manages draws, and oversees documentation.
Clear communication among all three is vital for a successful build.
How Funds Are Disbursed
After approval, the lender sets a draw schedule. Each draw is requested by the builder, inspected by the lender, and only then released. This process reduces the risk of misallocated funds and ensures construction stays on schedule.
What to Expect and How to Prepare
Construction loans typically come with higher interest rates than standard mortgages. You may be looking at 5.5% to 10%, depending on creditworthiness, lender, and market rates. Be prepared to provide detailed plans and budgets upfront.
Credit, Income, and Project Plans
To qualify, you’ll typically need:
- A credit score of 680 or higher
- A stable income and low debt-to-income ratio
- A licensed contractor
- Detailed building plans and cost estimates
Lenders are financing a project with no finished product to secure—so they want proof of viability.
How Much You Really Need
Expect to put down 20–25% of the total project cost. This helps mitigate the lender’s risk and demonstrates your financial commitment.
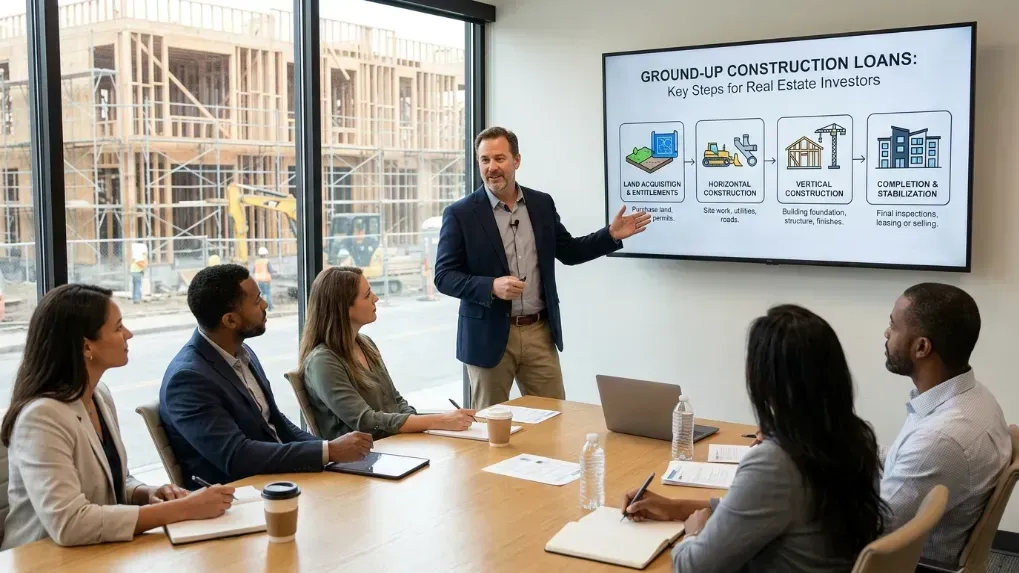
From Pre-Approval to Final Draw
Here’s a typical process:
- Pre-qualification
- Submit blueprints and cost breakdowns
- Appraisal based on “future value”
- Loan approval
- Begin construction
- Draws during each phase
- Final inspection and loan conversion or payoff
A Detailed Checklist
Here’s what you’ll need:
- Signed construction contract
- Building permits
- Architectural plans
- Contractor license and insurance
- Proof of land ownership
- Project budget
- Personal financial documents (W-2s, tax returns, bank statements)
When Traditional Lending Isn’t an Option
Traditional banks may hesitate with unconventional builds or borrowers with imperfect credit. That’s where a Hard Money Lender comes in—offering speed, flexibility, and approval based on asset value rather than strict credit criteria.
Budgeting and Communication
Keep meticulous records of every draw, expense, and inspection. Work closely with your builder and lender to anticipate delays or cost changes. Miscommunication can derail both timelines and budgets.
Delays, Cost Overruns, and What to Avoid
Risks include:
- Weather or labor delays
- Material shortages
- Permit complications
- Contractor disputes
Build in a 10–15% contingency into your budget to stay protected.
Insurance, Inspections, and Contracts
Secure:
- Builder’s risk insurance
- Liability insurance
- Regular inspections
- Ironclad contracts with all vendors
These steps protect your financial investment from fraud, accidents, or unfinished work.
Moving Into a Traditional Mortgage
Most construction loans are interest-only during the build. When construction ends, you can either:
- Refinance into a traditional mortgage
- Use a construction-to-permanent loan that automatically converts
Simplify the Process with One Approval
Construction-to-permanent loans offer one application, one closing, and a smoother transition. Once construction is complete, your loan morphs into a long-term mortgage with fixed monthly payments.
Pros and Pitfalls of DIY Projects
If you're acting as your own general contractor:
Pros:
- Save on labor
- More control
Pitfalls:
- Stricter qualification rules
- Time-consuming
- Lender skepticism
Few lenders allow this unless you have proven experience.
Government-Backed Options
- FHA Construction Loans: Lower credit score requirements
- VA Construction Loans: For eligible veterans with $0 down
These programs come with strict guidelines but offer more accessible paths for qualified borrowers.
When You’re Not Building From Scratch
Renovation loans, such as Fannie Mae’s HomeStyle or FHA 203(k), fund significant remodels. Perfect for:
- House flipping
- Upgrading old homes
- Converting properties
Short-Term Funding for Long-Term Projects
Bridge loans help cover expenses between buying new land and selling your current home. They’re short-term and ideal for fast-moving markets or complex financial situations.
What Real Estate Investors Need to Know
Investors use construction loans to:
- Build spec homes
- Develop multi-unit rentals
- Renovate flips
If you’re an investor looking for fast capital, a Hard Money Lender can streamline your funding with fewer hurdles.
Building the Home of Your Dreams
Construction loans support fully custom builds—from materials to layout. This is your chance to create a unique, energy-efficient, and fully personalized living space.
Questions to Ask Before You Commit
- How long is the loan term?
- Are draw inspections included in the cost?
- What happens if my project runs over budget?
- Can I convert the loan to a mortgage?
Asking the right questions helps you avoid surprises.
Timing is Everything
Apply for your loan after plans and costs are finalized but before breaking ground. Timing is key—apply too soon, and your permits may not be ready; too late, and you may face delays.
Speak to a Lending Expert
Choosing the right loan and lender is a game-changer. Reach out via the Contact page to get expert advice on your project.
Turning Your Blueprint Into a Home
Construction loans are complex, but they're also the key to unlocking a home that's truly yours. Whether you're building from scratch or flipping a fixer-upper, the right financial strategy makes all the difference. Educate yourself, ask smart questions, and lean on trusted professionals to bring your vision to life.
FAQs
Can I get a construction loan with bad credit?
Possibly. While banks may decline, a
Hard Money Lender might approve based on asset value.
How long does approval take?
Anywhere from 2–6 weeks, depending on documentation and lender type.
Do I make payments during construction?
Yes, but usually interest-only until the build is finished.
Can I include land purchase in the loan?
Yes, if the land isn’t already paid for, its cost can be wrapped into the loan.
What if construction takes longer than expected?
Most lenders allow for minor extensions but may require re-evaluation.
Is an appraisal required?
Yes. It’s based on the
projected value after construction.
Links