Is a Hard Money Loan Right for You? Key Signs It's Time to Consider One
Is a Hard Money Loan Right for You?
Financing real estate can feel like navigating a maze, with banks, credit unions, and private lenders offering countless options. Yet, sometimes the traditional lending routes simply don’t fit your needs. That’s where the question arises: Is a hard money loan right for you? This alternative financing method, often misunderstood, serves as a vital lifeline for many investors, entrepreneurs, and property buyers who need quick access to capital.
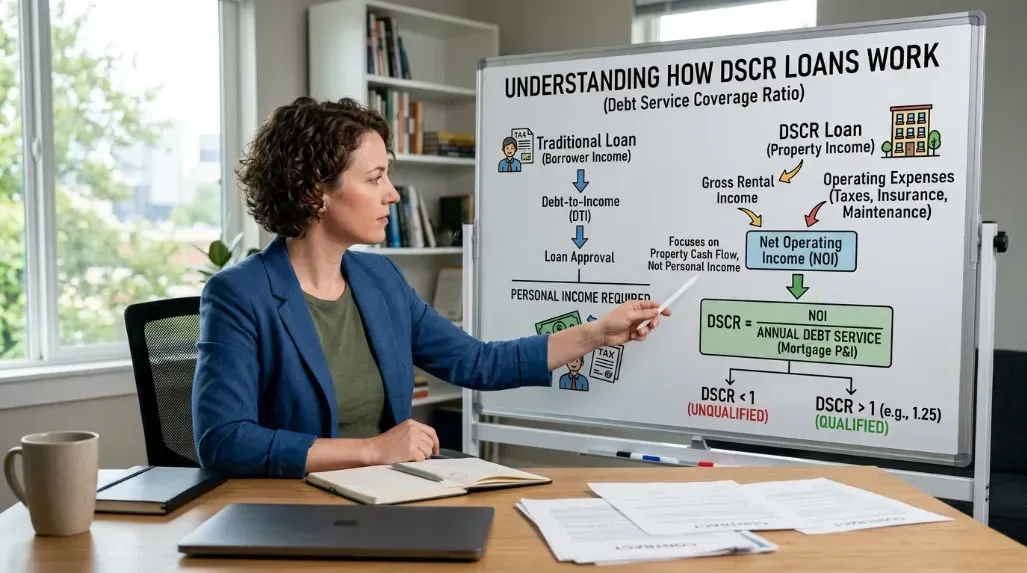
Unlike conventional loans that rely heavily on credit scores, tax returns, and income documentation, hard money loans focus primarily on the value of the property itself. Backed by private investors or companies, these loans are typically short-term, with higher interest rates and fees, but they offer unmatched speed and flexibility.
But how do you know when it’s time to consider this option? Let’s dive into the unmistakable signs that a hard money loan might be your ideal solution.
You Need Fast Funding to Close a Deal
Timing can be everything in real estate. Traditional lenders may take 30 to 60 days — sometimes even longer — to process your loan application. Meanwhile, that golden investment opportunity could slip right through your fingers.
If you’re bidding on a property with multiple offers, a fast close could set you apart from the competition. Hard money lenders are known for their ability to approve and fund loans in as little as a few days, providing you with a decisive advantage.
For instance, a Hard Money Lender can evaluate your deal and fund it within days, allowing you to seize profitable opportunities that others can’t.
Your Credit Profile Has Recent Issues
Let’s be honest: life happens. Medical bills, business setbacks, or personal challenges can temporarily damage your credit score. Traditional banks often see a lower FICO score as a red flag, but hard money lenders take a different view.
Since these loans are asset-based, the condition and value of the property carry more weight than your credit history. Even with a subpar credit score, you can secure financing if your property presents solid collateral.
The Property Requires Significant Renovation
Distressed properties often come with immense upside potential, but banks rarely want to finance projects with structural issues or major repairs. They prefer turnkey properties that pose minimal risk.
Hard money lenders, however, are experienced in funding fix-and-flip projects. If you’re eyeing a property with cracked foundations, outdated wiring, or leaky roofs, hard money may be your best bet. The lender recognizes the property’s after-repair value (ARV) and is willing to provide financing based on its future worth.
You Have Non-Traditional Income Sources
Self-employed entrepreneurs, gig workers, or business owners often face difficulties proving steady income to banks. Traditional underwriting requires tax returns, pay stubs, and W-2s — documents that may not reflect your true earning potential.
Hard money lenders cut through that red tape. They prioritize the asset over complicated income verification, making them ideal for borrowers with unconventional financial situations who still generate significant cash flow.
You're Investing in Unique or Riskier Properties
From mixed-use developments to commercial warehouses or even luxury vacation rentals, certain property types fall outside conventional lending guidelines. Traditional lenders categorize these as "non-conforming" and typically shy away from approving such loans.
Hard money lenders, on the other hand, specialize in these niches. They understand the unique nature of these assets and evaluate them on their profit potential, rather than rigid loan categories.
You Need Short-Term Bridge Financing
Hard money loans are often used as bridge loans — temporary financing solutions while you arrange long-term funding. For example, you might use a hard money loan to purchase a property quickly and then refinance it later with a conventional mortgage once renovations are complete or your financial profile improves.
The flexibility of hard money loans allows you to act swiftly without waiting for permanent financing to materialize.
You've Been Declined by Conventional Lenders
Even the most qualified buyers can sometimes face rejections from banks due to strict underwriting criteria. This doesn't necessarily mean you're a risky borrower — it often means your situation doesn't fit neatly into a bank's rigid policies.
Hard money lenders evaluate deals differently. If your project makes sense financially, they’re often willing to take the calculated risk that traditional lenders won’t.
The Advantages of Choosing a Hard Money Loan
There’s no denying that hard money loans come with higher interest rates and upfront fees. Yet for many borrowers, the benefits easily outweigh the costs.
- Speed: Closings within days rather than weeks.
- Flexibility: Customized loan terms based on the asset.
- Minimal Paperwork: Less focus on credit scores or employment documentation.
- Higher Loan Amounts: Based on ARV instead of current market value.
- Creative Solutions: Tailored to meet unique investment strategies.
By working with an experienced Hard Money Lender, you gain a partner who understands your financial goals and is willing to support them.
Potential Risks of Hard Money Loans
While hard money loans offer tremendous advantages, they aren’t suitable for everyone. Here are some risks to consider:
- Higher Interest Rates: Often double or triple conventional mortgage rates.
- Shorter Loan Terms: Typically 6 to 24 months.
- Higher Fees: Origination fees, appraisal costs, and other charges add up.
- Foreclosure Risk: Because loans are secured by property, defaulting can lead to swift foreclosure.
These loans require a well-thought-out exit strategy. Whether you plan to refinance, sell, or generate sufficient rental income, you must have a clear plan for repaying the loan within the agreed timeframe.
Is a Hard Money Loan Right for You?
After evaluating your situation, you might find that a hard money loan fits your needs perfectly. If you value speed, flexibility, and creative financing over low interest rates, this could be your smartest move.
However, it's vital to work with an experienced Hard Money Lender who can guide you through the process and structure a loan that aligns with your investment strategy.
FAQs
What credit score do I need for a hard money loan?
Most hard money lenders focus on the property rather than your credit score. Even borrowers with poor credit may qualify if the property provides sufficient collateral.
How quickly can I get funding with a hard money loan?
Hard money loans can often be funded in as little as 3 to 10 days, depending on the lender and complexity of the deal.
Are hard money loans only for real estate investors?
While investors commonly use them, hard money loans are also suitable for homeowners needing short-term bridge financing, business owners, and even contractors.
What happens if I can't repay a hard money loan?
If you default, the lender may initiate foreclosure since the loan is secured by your property. That's why having a clear exit strategy is critical.
How much can I borrow with a hard money loan?
Loan amounts typically range from 60% to 75% of the property’s after-repair value (ARV), though this varies by lender.
Is a hard money lender regulated like a bank?
Hard money lenders are typically private investors or companies, so they’re not regulated like banks. However, reputable lenders follow state lending laws and ethical practices.
When to Contact a Hard Money Lender
If you're ready to explore whether a hard money loan is right for your situation, don’t hesitate to Contact a trusted lender. Having an open conversation can help you understand the terms, process, and potential benefits customized to your needs.
Conclusion
Hard money loans aren’t for every borrower. But for those who need fast access to capital, flexible underwriting, and asset-based approvals, they serve as a powerful financial tool. Whether you're an investor flipping properties, a business owner needing bridge financing, or someone facing unique credit challenges, the key is to partner with an experienced Hard Money Lender who can structure a deal tailored to your success.
Always weigh the pros and cons carefully. With the right project, the right property, and the right plan, a hard money loan could unlock opportunities that would otherwise remain out of reach.
Links:
- Hard Money Lender: https://www.sandiegohardmoneylender.com/
- Contact: https://www.sandiegohardmoneylender.com/contact