How Bank Statement Loans Simplify Home Financing
Key Insights and Takeaways
Bank statement loans offer a powerful financing alternative for self-employed individuals and business owners. By evaluating actual monthly cash flow instead of tax returns, these programs help entrepreneurs secure real estate without sacrificing their legal tax deductions. Navigating the competitive San Diego market requires flexible, fast financing solutions tailored to your unique financial profile.
- Bypass W-2 Requirements: Qualify for a mortgage using 12 to 24 months of banking records instead of standard tax returns.
- Protect Tax Deductions: Continue taking advantage of business write-offs without ruining your chances of buying a property.
- Speed and Flexibility: Secure faster approvals in competitive real estate markets by working with specialized local lenders.

Buying a house is a major financial milestone. However, the mortgage process can feel incredibly frustrating for self-employed individuals. Traditional mortgage lenders rely heavily on standard employment forms. They want to see consistent W-2 tax documents. Freelancers, contractors, and business owners rarely have these documents.
This gap in the traditional financial system leaves many qualified buyers out in the cold. Fortunately, the lending industry has evolved. Alternative financing options now exist to bridge this exact gap. These specialized loan products focus on real cash flow rather than standard tax returns.
The Challenge for Self-Employed Buyers
Entrepreneurs face a unique dilemma when applying for a mortgage. A successful business owner might generate significant monthly revenue. But business owners also take advantage of legal tax deductions. They write off equipment, travel, and operational costs.
These deductions reduce their taxable income. Lower taxable income means they pay less in annual taxes. This is a smart business strategy. However, traditional banks look strictly at that net income number. On paper, the business owner suddenly looks like they cannot afford a mortgage.
This creates a massive roadblock. A business owner might have hundreds of thousands of dollars passing through their accounts. Yet a traditional bank will still deny their loan application. Buyers need a solution that looks at their actual purchasing power.
Understanding Bank Statement Loans
The solution to this problem is surprisingly straightforward. Bank statement loans bypass the traditional tax return requirements. Instead of analyzing tax deductions, lenders look directly at your banking history. They evaluate the deposits flowing into your accounts.
How the Verification Process Works
The verification process is entirely different from a conventional mortgage. Lenders typically request 12 to 24 months of consecutive banking statements. You can usually submit either personal or business account statements.
The underwriting team reviews these documents carefully. They calculate your average monthly deposits. This average deposit amount serves as your qualifying income. It provides a highly accurate picture of your actual monthly cash flow.
Protecting Your Tax Deductions
This alternative approach protects your business strategy. You do not have to choose between saving on taxes and buying a house. You can continue maximizing your legal write-offs. Your accountant can still do their job effectively.
At the same time, the lender sees the gross income entering your accounts. They understand that a business has expenses. Lenders usually apply a standard expense ratio to business accounts. This ratio calculates your true operational margins fairly.
Why San Diego Buyers Need Flexible Options
The real estate market in San Diego, CA moves incredibly fast. Desirable properties receive multiple offers within days of listing. Buyers must act quickly to secure their preferred properties.
Lengthy back-and-forth arguments with traditional banks will cost you deals. By the time a traditional bank finally denies a self-employed applicant, the property is already gone. Alternative financing provides the speed and flexibility needed to compete.
Local buyers need a financing strategy that matches the pace of the city. A streamlined income verification process means faster loan approvals. Faster approvals mean you can close on your dream property without unnecessary delays.

Preparing Your Financial Profile
Preparation makes the borrowing process much smoother. You should start organizing your financial documents well before you make an offer. Keep your banking statements clean and easy to read.
- Maintain separate accounts for personal and business finances.
- Avoid frequent overdrafts or negative balances.
- Ensure large, unusual deposits are easily explainable.
- Keep a steady flow of monthly deposits.
Clean financial records show lenders that you are a responsible borrower. Lenders want to see consistency and stability in your cash flow.
Exploring Other Real Estate Investment Options
Many self-employed individuals do not stop at buying a primary residence. Entrepreneurs naturally look for ways to grow their wealth. Real estate investment is a very popular wealth-building strategy.
Beyond the Primary Residence
You might decide to purchase distressed properties to renovate and sell. In this scenario, a fix and flip loan provides short-term capital for both purchase and construction costs.
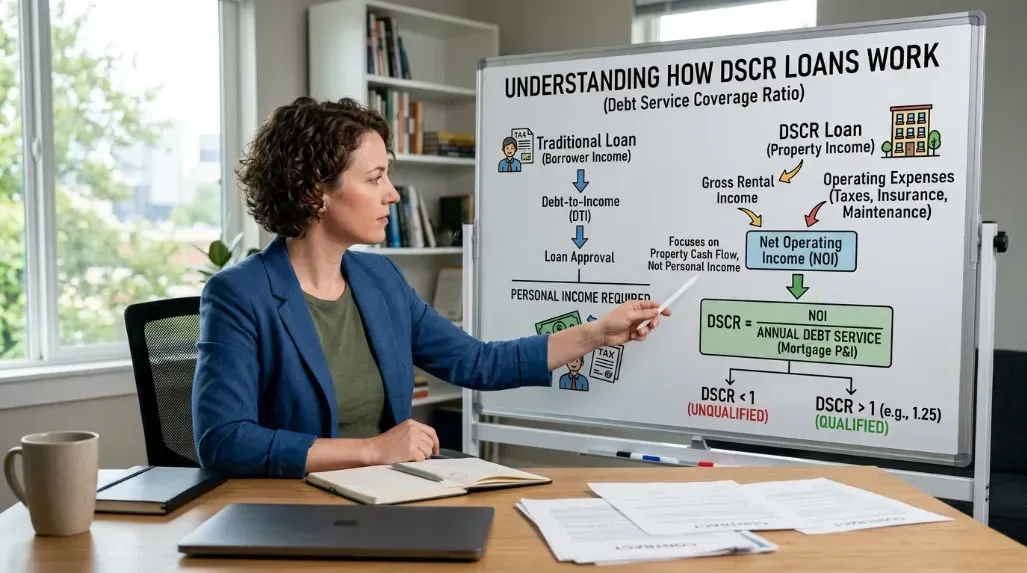
Alternatively, you might want to build a portfolio of rental properties. If you want to hold properties for long-term passive income, you should explore DSCR loans. These specific loans qualify you based on the property's rental income potential rather than your personal income.
As you expand your portfolio, education remains critical. It is very easy to miscalculate expenses on large projects. Make sure you read about the biggest multifamily loan mistakes to protect your hard-earned capital.
Partnering with Local Real Estate Experts
Navigating alternative financing requires a knowledgeable team. You need professionals who understand both lending guidelines and local market conditions. National banks often treat applicants like numbers on a spreadsheet.
Working with a dedicated local firm changes the entire experience. HWH San Diego Hard Money Lender - Real Estate specializes in helping buyers who do not fit the traditional mold. We structure financing around your actual financial strengths.
Our team believes in transparency and speed. You can read more about
our lending team background to understand our commitment to the local market. If you are ready to discuss your specific scenario, you can
reach out directly or simply call us at (619)983-0898. We are here to help you secure the funding you deserve.

Frequently Asked Questions
What are the main requirements for bank statement loans?
You generally need to provide 12 to 24 months of consistent banking records. Lenders will also look at your credit score and require a down payment. You do not need to provide standard tax returns or W-2 forms for this specific program.
Can I use my business bank accounts to qualify?
Yes, you can absolutely use business accounts. Lenders will review the gross deposits in the business account. They will then apply a standard expense factor to determine your qualifying income. Using personal accounts is also an acceptable option.
Do these programs require a perfect credit score?
A perfect credit score is not required. However, a higher score often results in better borrowing terms and lower interest rates. Lenders look at your overall financial health. Consistent cash flow and a reasonable down payment can help balance a slightly lower credit score.