How to Qualify for a Bank Statement Loan: A Step-by-Step Guide
Discover how to qualify for a bank statement loan in San Diego, CA. Learn what it is, why it matters, when to apply, and how a San Diego hard money lender can help you achieve your financial goals.
Introduction
For many self-employed professionals, entrepreneurs, and small business owners in San Diego, CA, traditional mortgage approvals can feel out of reach. Standard lenders typically ask for W-2s, pay stubs, and years of tax returns—documents that don’t always reflect the real income of independent earners. That’s where bank statement loans come in.
This type of financing lets you prove your income using your bank statements instead of tax returns. It’s a practical solution for San Diego residents whose cash flow doesn’t fit neatly into conventional lending boxes. In this article, we’ll walk you through what a bank statement loan is, why it matters, when to apply, and exactly how to qualify with a hard money lender in San Diego.
What is a Bank Statement Loan?
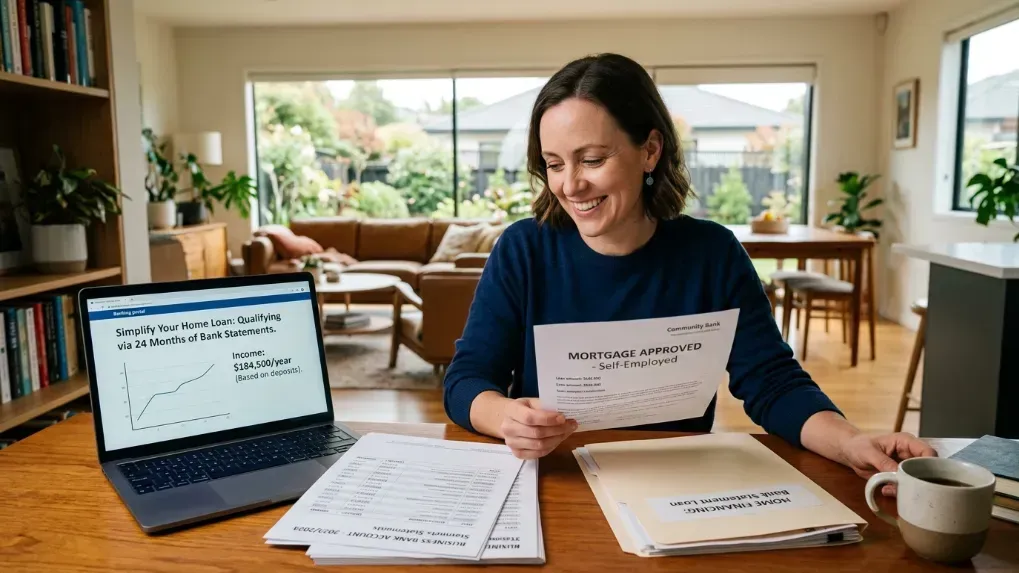
A bank statement loan is a mortgage option that allows borrowers to qualify based on their personal or business bank deposits rather than tax filings.
Instead of looking at adjusted gross income (which can be low after deductions), the lender reviews 12–24 months of bank statements to assess your real earning power.
Key Features:
- No W-2s or tax returns required
- Flexible for self-employed individuals
- Uses deposits to calculate income
- Available for both residential and investment properties
This flexibility makes bank statement loans especially attractive to freelancers, consultants, real estate investors, and business owners in San Diego, CA, where self-employment is common.
Why Bank Statement Loans Matter in San Diego, CA
San Diego’s economy thrives on innovation, small businesses, and freelance professionals. Many residents fall into income categories that don’t align with conventional mortgage requirements.
Local Considerations:
- High Property Prices: With home values above national averages, buyers need flexible lending solutions.
- Entrepreneurial Lifestyle: From digital agencies in North Park to surf shops in Pacific Beach, self-employment is common.
- Tax Deductions: Many San Diegans reduce taxable income through write-offs, making tax returns misleading for loan approvals.
According to a local lending specialist, “More than 25% of our borrowers in San Diego qualify better through bank statements than tax returns. It’s a smart path for independent earners.”
When Should You Consider a Bank Statement Loan?
Timing matters when choosing a mortgage. Here are scenarios when San Diego borrowers often turn to bank statement loans:
- Buying Your First Home: Especially if you’re self-employed and can’t show strong W-2s.
- Investing in Rental Properties: Great for leveraging income deposits to build wealth.
- Refinancing: If your tax returns understate your actual income.
- Seasonal Income: Perfect for those with fluctuating cash flow, like tourism-related businesses in San Diego.
Think of it as a bridge—when traditional paths are blocked, this option keeps your real estate goals moving forward.
How to Qualify for a Bank Statement Loan in San Diego, CA
Qualifying for a bank statement loan is straightforward if you know the steps. Here’s a breakdown:
Step 1: Gather Bank Statements
- Typically, lenders want 12–24 months of statements.
- Both business and personal accounts may be used.
Step 2: Calculate Average Deposits
- Lenders look at total deposits and average them monthly.
- Consistency matters more than one-time spikes.
Step 3: Check Credit Score
- Most San Diego hard money lenders require a 620+ score, though exceptions exist.
tep 4: Prepare a Down Payment
- Expect to put 10–20% down, depending on property type.
Step 5: Work With a Local Expert
- A hard money lender San Diego understands the local real estate market, which speeds approvals.
Bank Statement Loans vs. Traditional Mortgages
Here’s a side-by-side comparison to help you see the differences:
| Feature | Bank Statement Loan | Traditional Mortgage |
|---|---|---|
| Income Verification | Bank deposits | W-2s & tax returns |
| Best For | Self-employed | Salaried workers |
| Down Payment | 10–20% | 5–20% |
| Approval Time | Faster | Slower |
| Flexibility | High | Limited |
Checklist for San Diego Borrowers
Before applying for a bank statement loan, use this checklist:
- 12–24 months of bank statements
- Proof of business ownership (if applicable)
- Credit score above 620
- Down payment ready (10–20%)
- Property information (address, purpose)
- Work with a San Diego hard money lender
Local Insights from San Diego Experts
"One of the biggest benefits of bank statement loans in San Diego is speed," says a local hard money lender San Diego, CA. "With competitive property markets like ours, being able to close quickly can mean the difference between winning and losing the home you want."
Another borrower shared: “As a self-employed web designer, I never thought I could qualify. But with my bank statements, I got approved and moved into my condo in Mission Valley.”
Advantages of Working with a San Diego Hard Money Lender
Choosing a San Diego hard money lender has specific advantages:
- Local market expertise
- Faster approvals compared to national banks
- Flexible underwriting tailored to unique income profiles
- Personalized service and direct communication
For more information, check out the About Page.
Common Misconceptions About Bank Statement Loans
- Myth: They’re only for people with bad credit.
Reality: Many borrowers have good credit but unique income structures. - Myth: Interest rates are sky-high.
Reality: Rates are slightly higher than traditional mortgages but competitive in today’s market. - Myth: You can only use personal statements.
Reality: Both personal and business statements are acceptable.
FAQs
What is the minimum credit score for a bank statement loan in San Diego, CA?
Most lenders require at least a 620 credit score, though higher scores may qualify for better terms.
Can I use business bank statements to qualify?
Yes, business or personal statements can be used, depending on your income structure.
Are bank statement loans only for self-employed borrowers?
While most borrowers are self-employed, anyone with non-traditional income can apply.
How fast can I close with a San Diego hard money lender?
Many loans close within 2–4 weeks, much faster than traditional banks.
Do I need a large down payment?
Expect to put down between 10–20%, though this varies by property and lender.
Can I refinance using a bank statement loan?
Yes, many borrowers refinance to better reflect their income and reduce rates.
Conclusion
Qualifying for a bank statement loan in San Diego, CA is often simpler than people expect. By focusing on your actual bank deposits instead of complicated tax filings, this loan option opens doors for self-employed professionals, entrepreneurs, and investors.
With San Diego’s competitive housing market, working with a hard money lender San Diego gives you both speed and flexibility. If you’re ready to explore your options, visit our Borrower Loans Page or reach out through our Contact Page.
Key Takeaways
- Bank statement loans use deposits instead of tax returns to verify income.
- They’re ideal for self-employed San Diegans, investors, and freelancers.
- Expect to provide 12–24 months of bank statements, a solid credit score, and a 10–20% down payment.
- Working with a San Diego hard money lender offers speed, flexibility, and local expertise.
Ready to take the next step? Visit our Home Page to get started today.