What is the difference between a hard money loan and a traditional mortgage in San Diego?
If you live in San Diego, California, you may be wondering about your financing options when purchasing property or securing real estate investments. Between lengthy approval processes, strict qualification requirements, and competitive market conditions, navigating mortgage options can feel overwhelming and confusing.
At San Diego Hard Money Lender, we help San Diego residents understand financing options and make informed borrowing decisions that support their real estate goals. Whether you need quick funding for investment properties, bridge financing for fix and flip projects, or traditional home financing, expert lenders deliver knowledgeable guidance and customized solutions you can trust.
What Are Hard Money Loans and Traditional Mortgages?
Hard money loans and traditional mortgages represent two fundamentally different approaches to real estate financing. Understanding each type helps borrowers select the option that best matches their needs and circumstances.
Hard Money Loans: Short term loans secured by real estate, funded by private investors or companies, based primarily on property value rather than borrower creditworthiness.
Traditional Mortgages: Long term loans issued by banks, credit unions, or mortgage companies, based on borrower credit, income verification, and property appraisal.
Key characteristics include:
Hard money loans fund in days to weeks, not months
Traditional mortgages offer lower interest rates and longer terms
Hard money focuses on property value and equity
Traditional mortgages emphasize borrower credit and income history
Hard money works for investment properties and quick closings
Traditional mortgages suit primary residences and long term ownership
For example, a real estate investor in La Jolla can use a hard money loan to purchase a distressed property at auction, complete renovations quickly, and refinance into a traditional mortgage or sell for profit within months.
Why Understanding the Difference Matters in San Diego, California
San Diego's competitive real estate market creates unique financing challenges. With high property values, multiple offer situations, cash buyer competition, limited inventory, and fast moving deals, understanding financing options becomes essential for success.
Choosing the wrong loan type can cost you opportunities, money, and time. It can mean losing properties to faster funded offers, paying unnecessary fees, or being stuck with inappropriate loan terms. This makes loan type knowledge a critical skill for local buyers and investors.
According to the California Association of Realtors, properties in San Diego typically receive multiple offers, with cash and quickly funded deals often winning over traditionally financed offers. In fact, many San Diego investors have closed deals that would have been impossible with traditional financing by using hard money loans strategically.
As one of our lending specialists often says:
"Understanding the difference between hard money and traditional mortgages in San Diego is not just about financing. It's about matching the right tool to your specific real estate strategy and timeline."
Key Differences Between Hard Money Loans and Traditional Mortgages
Understanding the specific differences between these loan types helps you make informed decisions based on your situation, timeline, and investment strategy.
Approval Process and Timeline
Hard Money Loans: Approval in 24 to 48 hours, funding in 5 to 14 days based primarily on property value and equity position.
Traditional Mortgages: Approval in 1 to 2 weeks, funding in 30 to 45 days based on extensive documentation and underwriting.
Qualification Requirements
Hard Money Loans: Minimal credit requirements, no income verification needed, focuses on property value and exit strategy.
Traditional Mortgages: Credit score typically 620 or higher, full income documentation required, debt to income ratio limits, employment verification mandatory.
Interest Rates and Costs
Hard Money Loans: Interest rates from 8% to 15%, origination fees from 2% to 5% of loan amount, higher short term costs.
Traditional Mortgages: Interest rates from 6% to 8%, lower origination fees, significantly lower long term costs.
Loan Terms and Repayment
Hard Money Loans: Terms from 6 to 24 months, interest only payments common, balloon payment at term end.
Traditional Mortgages: Terms from 15 to 30 years, fully amortized payments, no balloon payment.
Loan Comparison Chart:
| Feature | Hard Money Loan | Email Address |
|---|---|---|
| Approval Time | 1 to 3 days | 7 to 14 days |
| Funding Time | 5 to 14 days | 30 to 45 days |
| Interest Rate | 8% to 15% | 6% to 8% |
| Loan Term | 6 to 24 months | 15 to 30 years |
| Hard Money Loan | Flexible | Strict (620+ score) |
| Income Verification | Not required | Required |
When to Use Hard Money Loans in San Diego
Hard money loans serve specific purposes and situations where speed, flexibility, or property condition make traditional financing impractical or impossible.
Fix and Flip Projects: Investors purchasing distressed properties for renovation and resale within months can benefit from specialized fix and flip loans designed for quick acquisitions and renovation funding.
Auction Purchases: Properties bought at foreclosure or tax auctions requiring immediate funding.
Bridge Financing: Short term funding while waiting for traditional financing or property sale.
Credit Challenges: Borrowers with credit issues who have valuable property equity.
Time Sensitive Deals: Situations requiring closing within days to secure competitive properties.
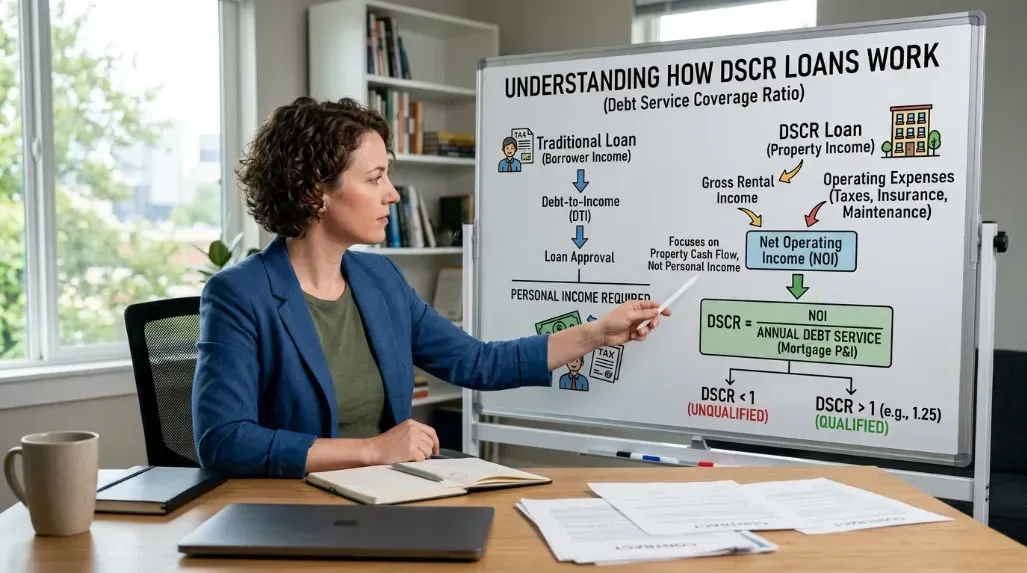
Non Owner Occupied Investment Properties: Rental properties or commercial investments, including those utilizing DSCR loans that focus on property cash flow rather than personal income.
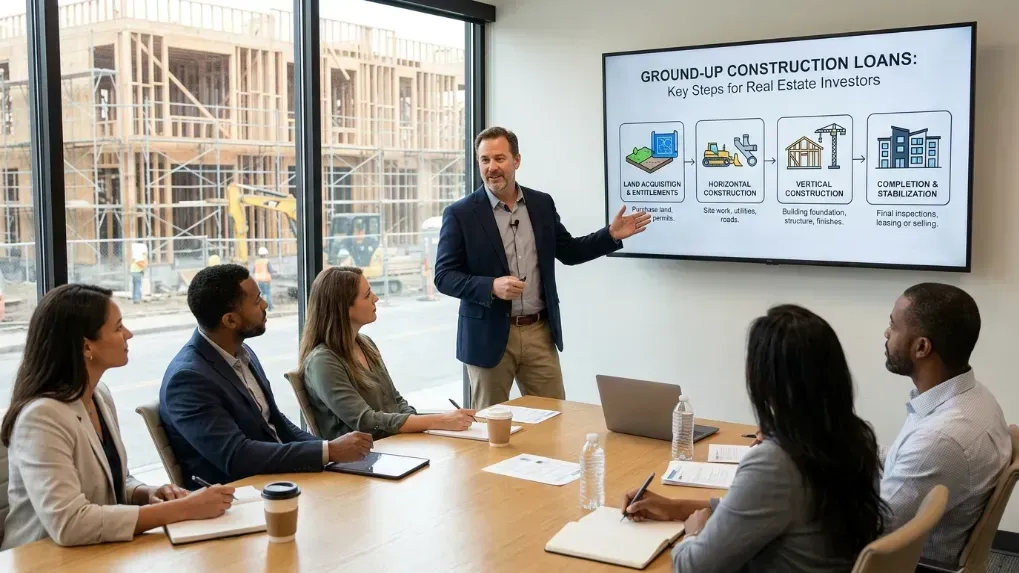
Ground Up Construction: Developers and investors building new properties from the ground up can access construction financing that provides funds in stages as the project progresses.
When to Use Traditional Mortgages in San Diego
Traditional mortgages work best for specific situations where lower costs, longer terms, and stability matter more than speed.
Primary Residence Purchase: Buying a home you'll live in long term benefits from lower rates.
Long Term Investment Properties: Rental properties you plan to hold for years or decades.
Strong Credit and Income: Borrowers who qualify easily benefit from significantly lower costs.
No Time Pressure: Situations where 30 to 45 day closing timelines work fine.
Lower Overall Costs: When minimizing interest payments over time is the priority.
Professional Lending Guidance in San Diego
Working with experienced lenders ensures you select the right financing option for your specific situation. Our team evaluates your needs systematically and provides clear recommendations.
Here's how our process works:
Initial Consultation: You contact us through our homepage with your property goals and timeline requirements.
Needs Assessment: We evaluate your situation, credit, timeline, and investment strategy.
Option Analysis: We compare hard money and traditional mortgage options for your scenario.
Rate Comparison: You receive clear rate quotes, terms, and cost comparisons for both options.
Recommendation: We provide expert guidance on which loan type best serves your goals.
Application Process: Once you choose, we guide you through the appropriate application and documentation.
Funding: Your loan funds according to the timeline, whether quick hard money or standard mortgage closing.
Once funded, you can move forward confidently with your real estate plans.
Borrower's Decision Making Checklist
Here's a quick checklist to help you choose between hard money and traditional mortgages in San Diego.
Step 1: Determine your timeline. Do you need funding in days or can you wait 30 to 45 days?
Step 2: Assess your credit and income documentation. Do you qualify easily for traditional financing?
Step 3: Calculate your holding period. Will you own the property short term or long term?
Step 4: Compare total costs. Which option costs less for your specific timeline and strategy?
Step 5: Consider your exit strategy. How will you pay off or refinance the loan?
Step 6: Contact experienced lenders to discuss your specific situation and get accurate quotes.
Expert Tips and Local Insights
In San Diego, choosing the right financing option can mean the difference between securing profitable deals and missing opportunities. Understanding local market dynamics helps you make strategic decisions.
"Hard money and traditional mortgages serve different purposes in San Diego's market. Trying to use traditional financing for time sensitive investment deals often results in lost opportunities, while using hard money for long term primary residence purchases wastes money on unnecessary costs," says one of our local lending specialists.
Whether you're in Downtown San Diego, North County, East County, or South Bay, matching your financing to your specific real estate strategy ensures success and maximizes your return on investment.
Common Scenarios in San Diego Real Estate
San Diego's diverse real estate market creates various situations where understanding loan differences becomes crucial. Recognizing common scenarios helps you plan appropriately.
Competitive Multiple Offer Situations: Hard money pre approval helps investors compete with cash buyers by demonstrating quick closing ability.
Distressed Property Purchases: Properties needing significant repairs often don't qualify for traditional financing, making hard money necessary.
Portfolio Building: Investors building rental portfolios often use hard money initially, then refinance into traditional mortgages once properties are stabilized.
Primary Residence with Unique Circumstances: Self employed borrowers or those with complex income may need hard money bridge loans before qualifying for traditional mortgages.
Estate Sales and Probate Properties: Time sensitive probate sales often require quick closing that only hard money can provide.
1031 Exchange Deadlines: Investors facing 1031 exchange deadlines may need hard money to close quickly and preserve tax benefits.
Conclusion
Understanding the difference between hard money loans and traditional mortgages in San Diego, California helps you choose the right financing for your specific real estate goals. By recognizing the approval timeline differences, qualification requirements, cost structures, and appropriate use cases, you can make informed decisions that support successful real estate transactions.
If you need guidance choosing between hard money and traditional mortgage financing for your San Diego property, contact us today to schedule your personalized lending consultation. Let's help you secure the right financing for your real estate success.
Key Takeaways
Hard money loans fund quickly (5 to 14 days) while traditional mortgages take 30 to 45 days
Hard money uses property value as primary criteria; traditional mortgages emphasize borrower credit and income
Hard money costs more short term but works for time sensitive deals and credit challenged borrowers
Traditional mortgages offer lower rates and longer terms, ideal for primary residences and long term holdings
The right choice depends on your timeline, property type, credit situation, and investment strategy.
Frequently Asked Questions:
What is the biggest difference between hard money and traditional mortgages in San Diego?
The biggest difference is speed and qualification criteria. Hard money funds in days based on property value, while traditional mortgages take weeks based on borrower creditworthiness and income.
Can I refinance a hard money loan into a traditional mortgage?
Yes. Many investors use this strategy, starting with hard money to acquire and improve property, then refinancing into a traditional mortgage for lower long term costs once the property is stabilized.
Which loan type is better for first time homebuyers in San Diego?
Traditional mortgages are almost always better for first time homebuyers purchasing primary residences due to significantly lower interest rates and longer, more affordable repayment terms.
Do hard money lenders check credit in San Diego?
Hard money lenders may check credit but don't have strict minimum requirements like traditional lenders. They focus primarily on property value and your exit strategy rather than credit scores.
What happens if I can't pay off a hard money loan at the end of the term?
You'll need to refinance into another loan, sell the property, or negotiate an extension with your lender. Planning your exit strategy before taking a hard money loan is essential to avoid this situation.
How do I decide which loan type is right for my San Diego property?
Consider your timeline, credit situation, property type, holding period, and overall strategy. Contact experienced lenders who can analyze your specific situation and recommend the most appropriate financing option.