Hard Money Loan Brokers Explained: What They Do and How They Work
When it comes to real estate financing, time can be the difference between landing a great deal and watching it slip away. This is where hard money loan brokers come in — specialists who connect borrowers with lenders that can provide quick, asset-based funding when traditional banks can’t deliver in time.
Unlike conventional mortgage processes that often take weeks or months, hard money financing can close in days. And while it may cost more in interest, for many real estate investors, the speed and flexibility are worth every penny.
What is a Hard Money Loan Broker?
A hard money loan broker is a middleman — but not in the negative sense. Instead, they act as a bridge between a borrower seeking funds and a private or institutional lender willing to provide a hard money loan.
Instead of relying heavily on a borrower’s credit score, hard money lenders focus on the value of the property being used as collateral. Brokers help navigate this process by finding the right lender match and structuring a deal that works for both sides.
If you’re looking for a reputable lending partner, you might start by connecting with a trusted hard money lender that works closely with experienced brokers.
How Hard Money Loan Brokers Differ from Traditional Loan Officers
While both brokers and loan officers arrange financing, they operate differently:
Feature Hard Money Loan Broker Traditional Loan Officer
Funding Source Private lenders, hedge funds, individuals Banks, credit unions
Approval Focus Property value, equity Credit score, income, debt ratio
Speed Days Weeks or months
Flexibility High Low to medium
Loan Types Short-term, bridge, fix-and-flip Conventional, FHA, VA
For real estate investors who need speed and flexible terms, brokers in the hard money space are often the preferred choice.
Core Responsibilities of Hard Money Loan Brokers
A hard money loan broker’s role involves:
- Assessing the borrower’s needs and goals.
- Analyzing the property’s value and potential.
- Matching the borrower with an appropriate lender.
- Negotiating loan terms, fees, and repayment schedules.
- Coordinating paperwork and closing procedures.
Their goal is to remove as much friction as possible from the funding process.
The Process of Working with a Hard Money Loan Broker
Working with a broker usually follows this step-by-step path:
- Initial Consultation – You explain your project, timeline, and funding needs.
- Property Evaluation – The broker collects details, appraisals, and comps.
- Loan Proposal – They pitch your deal to one or more lenders.
- Term Negotiation – Rates, terms, and repayment schedules are set.
- Due Diligence – Title checks, insurance, and documentation are completed.
- Closing – Funds are wired, often within a week.
For investors juggling multiple deals, this streamlined process can be invaluable.
Types of Loans Handled by Hard Money Loan Brokers
Brokers arrange a variety of funding options:
- Fix-and-Flip Loans – Short-term financing for property rehab and resale.
- Bridge Loans – Temporary funding until long-term financing is secured.
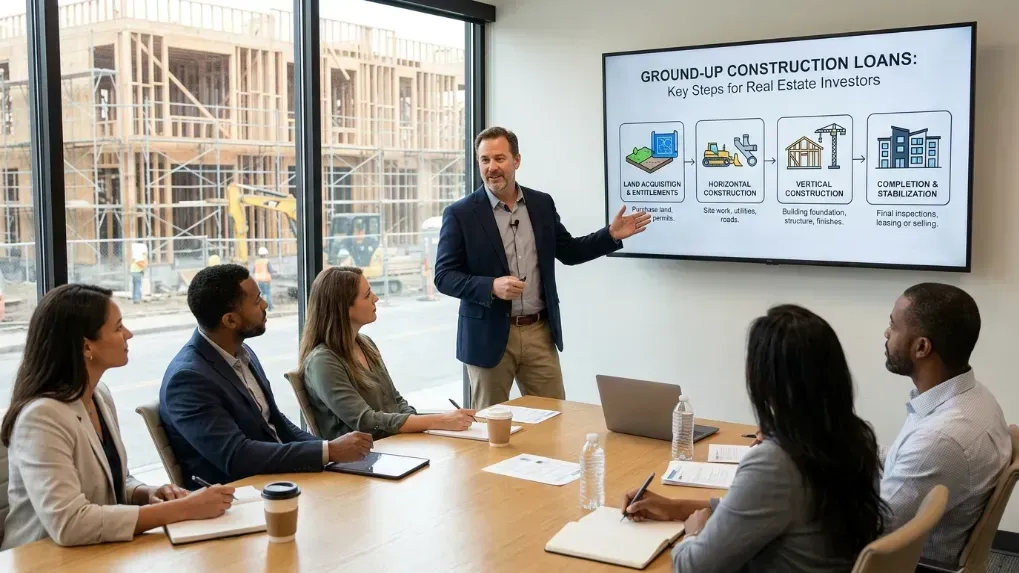
- Construction Loans – For building or major renovations.
- Commercial Property Loans – For income-producing real estate.
- Cash-Out Refinance – Tapping equity for new investments.
Why Real Estate Investors Use Hard Money Loan Brokers
Speed, flexibility, and deal-making expertise are the top reasons investors rely on brokers. With competitive real estate markets, waiting on traditional banks can mean losing out on a prime opportunity.
Brokers often know which lenders specialize in certain deal types, saving investors from wasting time on mismatched applications.
How Brokers Connect Borrowers to Hard Money Lenders
Networking is everything. Brokers build relationships with private lenders over time, learning their risk appetite, preferred property types, and geographic focus.
When an investor comes with a deal, the broker can quickly match them with a lender who’s likely to approve and fund it. This matchmaking ability is one of the broker’s greatest assets.
Evaluating a Borrower’s Needs and Loan Criteria
Before a deal can move forward, brokers assess:
- Loan-to-value ratio (LTV).
- Property type and location.
- Borrower’s exit strategy.
- Projected timeline for repayment.
The clearer and more realistic these factors are, the smoother the process will be.
Understanding Hard Money Lender Requirements
Most hard money lenders require:
- A down payment or equity stake.
- A clear title and property insurance.
- Documentation of property value (appraisal or comps).
- A defined exit strategy (sale, refinance, etc.).
Working with a broker ensures you know these requirements upfront, avoiding surprises later.
Risks and Challenges in Hard Money Loan Brokerage
Like any business, hard money loans have risks:
- Higher interest rates compared to conventional loans.
- Short repayment timelines.
- Potential for borrower default.
- Market downturns affecting property value.
A good broker helps mitigate these risks by structuring deals carefully.
Regulations and Licensing for Hard Money Loan Brokers
Regulations vary by state, but most require:
- A real estate or mortgage broker license.
- Compliance with usury laws and disclosure requirements.
- Following advertising and fair lending rules.
Some states also require ongoing education to maintain a license.
How Brokers Earn Money
Brokers are typically paid through:
- Origination Fees – Charged as a percentage of the loan.
- Broker Fees – Flat or percentage-based compensation.
- Points – A portion of the interest collected at closing.
Fees are disclosed in advance to maintain transparency.
Qualities of a Successful Hard Money Loan Broker
Successful brokers share traits like:
- Strong communication skills.
- Industry knowledge and market insight.
- Negotiation expertise.
- Large lender network.
- Integrity and transparency.
Choosing the Right Hard Money Loan Broker
When selecting a broker, consider:
- Experience in your specific type of deal.
- Client reviews and testimonials.
- Licensing and credentials.
- Response time and availability.
If you’re ready to discuss your project with a professional, don’t hesitate to contact a hard money lender to get the conversation started.
Common Myths About Hard Money Loan Brokers
- Myth: They’re too expensive.
Reality: While rates are higher, the speed often offsets the cost. - Myth: Only for desperate borrowers.
Reality: Many savvy investors use them strategically. - Myth: Deals aren’t safe.
Reality: Licensed brokers follow strict compliance rules.
Future Trends in Hard Money Loan Brokerage
The industry is evolving with:
- Online lending platforms speeding up approvals.
- AI-driven property valuation tools.
- Broader investor pools funding loans.
- More transparency through digital document sharing.
These trends mean faster deals and greater opportunities for both brokers and borrowers.
Conclusion
Hard money loan brokers play a crucial role in connecting borrowers with the right private lenders. They bring speed, expertise, and flexibility to real estate financing, often helping investors secure deals that would be impossible through traditional channels.
By understanding what they do and how they operate, borrowers can make smarter decisions and leverage these professionals to maximize their investment opportunities.
FAQs
What does a hard money loan broker do?
They connect borrowers with private lenders, negotiate terms, and facilitate fast real estate financing.
Are hard money loans only for bad credit borrowers?
No. Many borrowers use them for speed and flexibility, not because of poor credit.
How fast can a hard money loan close?
Some close in as little as 3–7 days.
Do brokers charge upfront fees?
Some charge an application or processing fee, but most earn through loan origination fees.
Are hard money loans risky?
They carry higher interest and shorter terms, but risks can be managed with proper planning.
Can I use a hard money loan for a rental property?
Yes, though most are short-term loans designed for flips, construction, or quick acquisitions.