Bridge Loans Explained: Your Guide to Short-Term Real Estate Financing
When navigating the world of real estate, timing is everything. Whether you're a homeowner juggling the sale and purchase of properties or a savvy investor eyeing the next big flip, access to quick and flexible funds can make or break a deal. This is where bridge loans come into play—your financial stepping stone when traditional options are too slow or restrictive.
Bridge loans explained in simple terms are short-term loans designed to “bridge” the gap between the need for immediate cash and the availability of permanent financing. These loans are tailored for urgency, giving real estate buyers the leverage they need to seize opportunities fast.
Let’s walk through this comprehensive guide and explore how bridge loans work, when to use them, and why they might be the smart solution for your next move.
What is a Bridge Loan?
A bridge loan is a short-term financing option typically used in real estate transactions. It "bridges" the gap between the sale of your current property and the purchase of a new one. Unlike conventional loans that take weeks to process, bridge loans are much quicker, often closing in a matter of days.
They’re secured by collateral—usually real estate—and serve as a temporary funding solution until the borrower can either sell their property or secure long-term financing.
How Do Bridge Loans Work?
Bridge loans operate on a simple concept: speed. Lenders evaluate the value of your current property and offer you a percentage of its worth, which you can use to secure your next property.
Key Features of Bridge Loans:
- Term Length: Typically 6–12 months, extendable to 18–24 months in some cases.
- Collateral-Based: Backed by the equity in real estate.
- Fast Funding: Often processed and funded within 5–10 business days.
- Interest-Only Payments: Many bridge loans require interest-only monthly payments until maturity.
When Should You Use a Bridge Loan?
Bridge loans aren’t for everyone—but in certain situations, they’re a perfect fit.
Common Scenarios Include:
- Buying a new home before selling your current one.
- Snagging an investment property at auction.
- Preventing foreclosure or paying off balloon loans.
- Financing property renovations before refinancing.
In such time-sensitive scenarios, speed is non-negotiable—and that's exactly what bridge loans offer.
Types of Bridge Loans
Depending on your needs, there are different types of bridge loans available:
- Residential Bridge Loans – For homeowners moving from one home to another.
- Commercial Bridge Loans – For businesses purchasing or renovating income-producing properties.
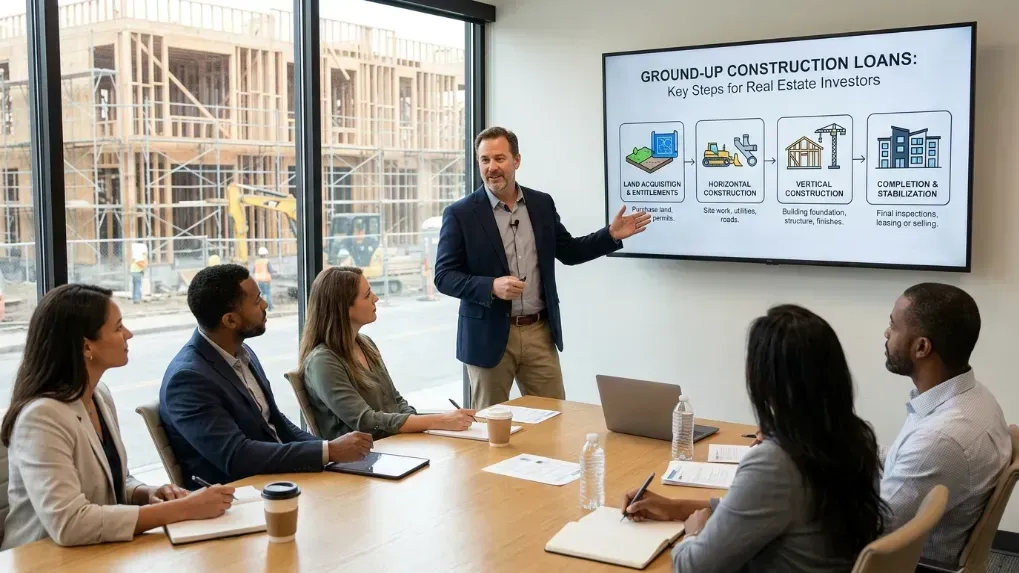
- Construction Bridge Loans – Ideal for developers needing funds before long-term financing kicks in.
Benefits of Bridge Loans
Bridge loans come with a bouquet of benefits for both homeowners and investors:
- Speed to Close: Ideal for time-sensitive deals.
- No Income Verification (in many cases): Especially in asset-based lending.
- Equity Leverage: Tap into your home’s equity to move forward.
- Flexible Terms: Customizable to fit unique situations.
Check out our Financing Service to see tailored loan programs that fit your investment or home-buying needs.
Risks and Considerations
Before jumping in, consider the flip side:
- Higher Interest Rates: Typically between 7% and 12%.
- Short Repayment Period: May cause pressure to sell or refinance quickly.
- Fees and Closing Costs: Points, origination fees, and legal fees add up.
So, are they risky? A bit. But if used strategically, bridge loans can be your golden ticket to real estate success.
Bridge Loan Requirements
Lenders are mainly focused on collateral and exit strategy. Here's what you’ll likely need:
- A minimum of 20–30% equity in the current property.
- A clear exit strategy (sale or refinance).
- Basic documentation (title, mortgage statement, property taxes).
- Good-to-fair credit score (although some lenders are lenient).
Bridge Loans for Investors
Investors often use bridge loans for:
- Fix-and-flip projects
- Buying auction properties
- Funding multi-family units quickly
Bridge loans fuel speed and agility—traits every investor needs in a competitive market.
Alternative Short-Term Financing Options
Not sure if bridge loans are the answer? Consider:
- Hard Money Loans – Similar but more flexible and often used in real estate investing.
- HELOCs – Home Equity Line of Credit; best for long-term needs.
- Personal Loans – Good for small funding gaps with fast approvals.
Tax Implications
While interest on bridge loans is often tax-deductible if used for investment purposes, it’s always best to consult with your CPA. Keep documentation ready for your year-end tax prep.
Legal Considerations
Check your state’s regulations regarding short-term lending. Some states cap interest rates, require licensing, or enforce borrower protections. Always read the fine print or consult an attorney.
How to Choose the Right Lender
Here’s what to look for:
- Transparent fee structure.
- Quick underwriting process.
- Positive client testimonials.
- License and compliance certifications.
Need help? Reach out through our Contact page for personalized assistance.
FAQs
What is the typical interest rate on a bridge loan?
It generally ranges from 7% to 12%, depending on lender and borrower risk profile.
Can I use a bridge loan for commercial properties?
Yes! Commercial bridge loans are common in real estate investment and business expansion.
Do I need good credit for a bridge loan?
Not always. Many private lenders focus more on asset value than credit score.
Are bridge loans risky?
They can be if you don’t plan your exit strategy properly. But with the right preparation, they’re manageable.
How fast can I get a bridge loan?
Most close within 5–10 business days.
Do bridge loans show on your credit report?
Yes, if reported by the lender. It can affect your credit, so manage responsibly.
Conclusion
Bridge loans are powerful tools in the real estate financing toolkit. When used wisely, they unlock doors that would otherwise remain closed. They offer speed, flexibility, and freedom—but also require strategy, planning, and caution.
Whether you're a homebuyer needing a quick close or an investor seeking the next big opportunity, bridge loans can be your secret weapon. Just ensure you work with a reputable lender, understand the terms, and have a solid repayment plan.
For tailored advice, visit our Financing Service or connect through our Contact page to get started today.
Links: