DSCR Loan Basics: How They Work and Why They Matter
Discover DSCR Loan Basics: How They Work and Why They Matter. Learn how debt service coverage ratio loans help investors, how they’re calculated, and why they’re a smart choice for property financing.
Introduction to DSCR Loans
In today’s dynamic real estate market, access to flexible financing is key. That’s where DSCR loans step in — becoming a popular option for investors who want to leverage rental income instead of traditional employment income. But what exactly are DSCR loans, and why are they making waves in property investment circles?
Whether you're a seasoned investor or just entering the game, understanding DSCR loan basics can help you make smarter financial decisions. Let's break down what these loans are, how they work, and why they might be the perfect fit for your next real estate venture.
What is a DSCR Loan?
A DSCR loan is a type of real estate loan where qualification is primarily based on the property’s income potential rather than the borrower’s personal income.
DSCR Loan Meaning and Definition
DSCR stands for Debt Service Coverage Ratio. Lenders use this ratio to determine whether a property generates enough income to cover its debt obligations — mainly the loan’s principal and interest payments.
Difference Between DSCR Loans and Traditional Loans
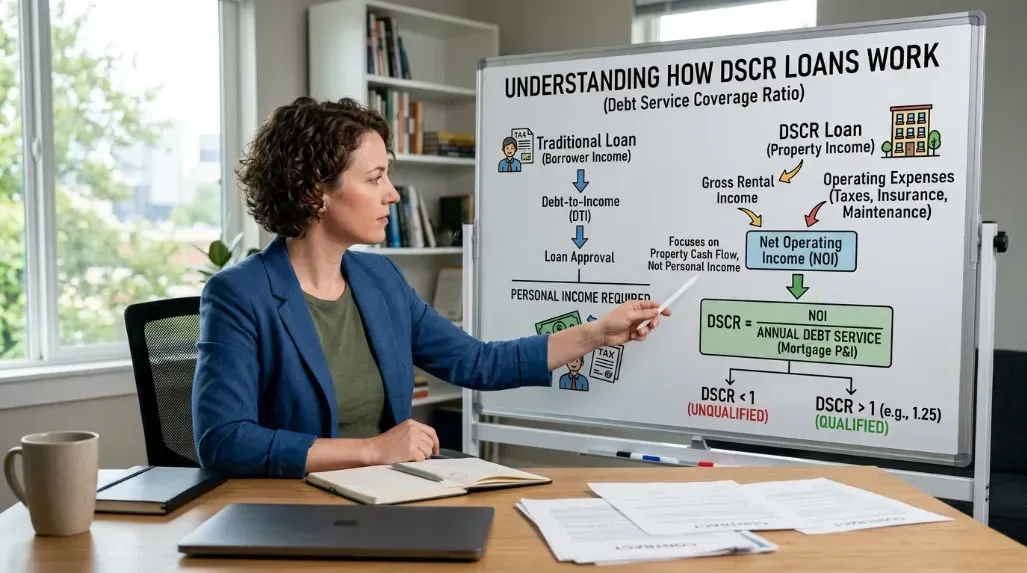
Unlike conventional mortgages, which require income verification, W-2s, and tax returns, DSCR loans rely more heavily on the rental income the property generates. This allows self-employed borrowers or real estate investors to qualify more easily — even without a job.
Understanding Debt Service Coverage Ratio (DSCR)
Formula and Calculation of DSCR
The DSCR formula is simple:
DSCR = Net Operating Income (NOI) / Total Debt Service
For example, if a property earns $10,000 monthly and the mortgage payment is $8,000, the DSCR is:
$10,000 ÷ $8,000 = 1.25
This means the property earns 25% more than needed to pay the loan.
Ideal DSCR for Loan Approval
Most lenders look for a minimum DSCR of 1.2. This gives them confidence that the property earns enough to comfortably pay the mortgage and other expenses.
Why DSCR Matters in Real Estate Investing
How DSCR Affects Loan Risk
DSCR is a risk metric. A high ratio signals low risk, meaning the property is generating solid cash flow. On the other hand, a DSCR below 1.0 indicates the property isn’t bringing in enough money to pay its debts.
Lender’s Perspective on DSCR
Lenders want assurance that your property won’t default. A strong DSCR is their peace of mind. It's why Hard Money Lenders like San Diego Hard Money Lender use this ratio as a critical benchmark when approving loans.
How DSCR Loans Work
Qualifying for a DSCR Loan
To qualify, lenders evaluate the property's monthly rent compared to the projected loan payments. If the rental income sufficiently covers the mortgage, you're likely in good shape.
Role of Rental Income in DSCR
The property's rent is king. That’s what drives the calculation — not your salary. Lenders typically use market rents or actual leases to estimate income and assess whether the loan is viable.
Who Can Benefit from DSCR Loans?
Real Estate Investors
If you’re flipping homes or building a rental portfolio, DSCR loans are perfect. They help you grow your holdings without overextending your personal credit.
Self-Employed or No-Income Verification Borrowers
Freelancers, entrepreneurs, and gig workers often find it hard to qualify for traditional loans. DSCR financing opens the door for them — no income tax returns required.
DSCR Loan Requirements and Eligibility
Minimum Credit Score
While each lender varies, most prefer a credit score of 620 or higher. The better your credit, the better your terms.
Documentation Needed
Even though income isn’t verified, you’ll need:
- A lease agreement
- Property appraisal
- Bank statements
- Down payment proof
Pros and Cons of DSCR Loans
Key Benefits
- No personal income verification
- Ideal for investors
- Quick approvals
- Flexible property types
Possible Drawbacks
- Higher interest rates than conventional loans
- May require a larger down payment (20–30%)
- Lower DSCR may result in denial
DSCR Loan vs Conventional Loan
Key Comparisons
Feature DSCR Loan Conventional Loan
Based On Rental Income Personal Income
Income Verification Not Required Required
Approval Speed Fast Slower
Down Payment 20-30% 5-20%
When to Choose One Over the Other
If your rental property is cash-flowing, and your personal income is hard to verify, DSCR loans win hands down.
How to Calculate DSCR Accurately
Common Mistakes in DSCR Calculation
- Forgetting to subtract operating expenses
- Ignoring property taxes and insurance
- Using gross rent instead of net income
DSCR Calculators and Tools
Many lenders provide online DSCR calculators. Just input your rental income, operating expenses, and loan payments to get an instant estimate.
Types of Properties Financed with DSCR Loans
Single-Family Rentals
DSCR loans are great for financing individual rental homes, especially if you’re just getting started.
Multifamily and Commercial Properties
You can also use them for duplexes, apartment buildings, or mixed-use spaces — as long as the income supports the debt.
Best Practices to Qualify for a DSCR Loan
Boosting DSCR Score
- Increase rent
- Reduce expenses
- Refinance to lower your payment
Maintaining Strong Rental Income
Keep vacancy low. Maintain your property. Rent to qualified tenants. All these actions help keep your DSCR in a healthy range.
DSCR Loan Rates and Terms
Average Interest Rates
DSCR loans generally have rates between 7% and 9%, depending on your credit, property type, and loan size.
Common Loan Periods
Terms usually range from 30-year fixed mortgages to 5/1 ARMs, with options for interest-only periods.
DSCR Loans and Cash Flow Management
Impact on Monthly Cash Flow
Since DSCR focuses on rental income vs. mortgage, managing that spread is crucial. A positive DSCR ensures you don’t dip into savings each month.
Planning for Profitability
Smart investors calculate DSCR before buying. That way, they know whether the investment will be a winner from day one.
Why Choose a Hard Money Lender for DSCR Loans
Working with a Hard Money Lender offers speed, flexibility, and access to loans banks won’t touch.
Flexibility in Approval
Hard money lenders don’t follow the same rules as banks. They look at the asset — not your pay stub.
Fast Funding Process
You could be funded in 7–14 days — ideal for hot deals that need quick action.
DSCR Loan Basics: How They Work and Why They Matter
The core of a DSCR loan lies in one thing: Can your property pay for itself? If the answer is yes, you're looking at a flexible, investor-friendly loan that’s far easier to qualify for than traditional mortgages.
FAQs About DSCR Loans
What does DSCR stand for?
DSCR stands for
Debt Service Coverage Ratio. It measures a property’s ability to cover loan payments from its rental income.
What DSCR is considered good?
A
DSCR of 1.2 or higher is typically required, though some lenders may accept 1.0 if other factors are strong.
Do I need to show income for a DSCR loan?
No. These loans are
based on rental income, not personal employment income.
Can I get a DSCR loan with bad credit?
Possibly. Many lenders accept credit scores as low as
620, but terms may be less favorable.
Are DSCR loans only for investors?
Yes, these loans are designed for
investment properties, not primary residences.
How fast can I close a DSCR loan?
With the right lender, you can close in
as little as 7–14 days.
Case Study: A Successful DSCR Loan Experience
John, a full-time contractor, wanted to expand his rental portfolio but couldn’t qualify for a traditional mortgage. Using a DSCR loan, he bought a triplex where the combined rent exceeded the mortgage. Without submitting a single tax return, he secured funding in 10 days through a Hard Money Lender and now enjoys positive monthly cash flow.
Conclusion: Are DSCR Loans Right for You?
DSCR loans offer a unique path for investors who may not fit inside the “conventional borrower box.” If you own or plan to acquire cash-flowing rental property, this type of loan can unlock powerful opportunities — with less red tape and more speed.
If you want to discuss your specific scenario or see if you qualify, don’t hesitate to contact an expert lender who specializes in DSCR financing.
Links